 By Benjamin Roure L'Hermitte
A stock trading journal is the record of your stock trades, completed with what exists only in this market: the company and its sector, the quarterly earnings calendar, dividend dates and, in the US, the margin rules that frame day trading. A stock isn't just a ticker going up or down, and these extra layers demand a reading grid that a generic journal doesn't provide by default.
- Earnings dates and the opening gaps they cause form a separate risk category, to tag explicitly.
- Sector tagging reveals whether your edge is truly generalist or concentrated in a single industry.
- The pattern day trader rule has been replaced since June 4, 2026 by an intraday margin standard, which your broker has until October 20, 2027 to apply.
- Dividend dates are a minor but real factor to keep in mind, especially with options.
Stock trading stands apart from other instruments because every ticker is tied to a real company, with its own calendar events, sector dynamics, and, for margin accounts in the US, rules specific to day trading. A journal that treats every stock as an interchangeable ticker misses these layers of information. That starts with understanding stock trading itself.
This guide details what a stock trading journal needs to track beyond a generic journal: earnings dates and gaps, sector, the US margin rule on day trading, and dividend dates. For the basics common to every market, see our trading journal guide; if you keep your trade log in a spreadsheet, our Excel template gives you the base columns to extend.
Earnings and gaps, a risk category of their own
A stock can open several percent away from its previous close, a gap, generally triggered by a quarterly earnings announcement, sector news, or macro news that happened outside trading hours: the day's first price comes out of an opening auction, which begins at 9:30 a.m. New York time according to the NYSE's auctions page, and everything that happened since the close lands in it at once. This type of move has nothing to do with a normal intraday move: it jumps straight over your stop, and as the SEC's investor bulletin on stop orders recalls, the stop price is not a guaranteed execution price but a trigger that turns the order into a market order. Your usual risk management is moot for that specific trade.
A rigorous stock journal should explicitly tag trades taken near or during an earnings window, because the risk profile simply isn't the same. A trader who blends their usual technical trades with trades taken intentionally or accidentally around an earnings announcement in the same statistics ends up with a distorted picture of their real edge on each of these two categories, which shouldn't be judged with the same yardstick.
Sector tagging, to see where your edge really lives
A stock trader may believe in a generalist edge, applicable to any ticker, when their performance is in reality concentrated in one or two sectors they know better or that fit their style better. Without a sector tag (tech, energy, healthcare, finance, consumer, and so on) in the journal, this concentration stays invisible.
| What the sector tag reveals | Why it's useful |
|---|---|
| Edge concentrated in one sector | You can specialize consciously instead of spreading focus thin |
| Underperformance in a specific sector | You can exclude it or adjust your sizing there |
| Dependence on a sector cycle | Understand why performance varies over time |
| Hidden correlation between positions | Several tickers in the same sector often move together |
That last point echoes a concern found in other markets under a different name: positions open on several tickers in the same sector can move together on a piece of sector news, turning what looked like three diversified bets into one concentrated bet. Sector tagging lets you spot that concentration before it turns into a grouped loss.
The pattern day trader rule and what replaces it
In the US, the so-called pattern day trader rule long framed day trading on margin accounts: according to the SEC's entry on the pattern day trader, a customer who executed four or more round-trips (buying and selling the same stock the same day) within five business days was designated as such and had to keep at least $25,000 in the account, or the broker restricted their day trading. That rule is being replaced: FINRA's Regulatory Notice 26-10 sets June 4, 2026 as the effective date of an intraday margin standard that removes the day trade count and the $25,000 minimum, and gives brokers until October 20, 2027 to switch. The broker now computes an intraday margin deficit, to be met as promptly as possible; a customer who repeatedly fails to meet it within five business days is barred from creating or increasing a short position or debit balance for 90 days. FINRA's explainer sums it up in one line, there is no $25,000 minimum equity requirement for day trading anymore, and warns that your broker may keep applying the old rule during the transition. Who was affected, and how each broker switches, is covered in the article on the pattern day trader rule and in the one on whether day trading is legal.
For your journal, the consequence depends on the account. On a margin account at a broker that has switched, what you track is no longer the number of round-trips but the margin used during the session and how fast a deficit is met; at a broker still applying the old rule, the day trade count over five rolling days remains the line to hold, so you don't discover the limit mid-session and have to change your plan under time pressure. On a cash account, the constraint is settlement: the proceeds of a sale are only available on the settlement date, the day funds and securities must be delivered, and FINRA's page on settlement cycles states that it falls on the next business day after the trade, T+1, as of May 2024, a date the SEC set at May 28, 2024. In the European Union, settlement is not yet at T+1: ESMA recommends October 11, 2027 for the move. Logging the settlement date next to the trade date keeps you from counting the same capital twice.
Dividend dates, a minor but real factor
Paying a dividend comes with an adjustment to the stock price on the day the shares trade without the dividend right, the ex-date: the SEC's page on ex-dividend dates states that whoever buys on that day or after does not receive the dividend, and that with a significant dividend, the price may fall by that amount on the ex-dividend date. This move has nothing to do with the trade's technical or fundamental analysis and can distort a chart's reading if you don't know it happened, particularly on high-yield stocks where the adjustment is visible. A stock split produces the same kind of jump, only bigger: the SEC's glossary defines it as an increase in the number of shares without a change in shareholders' equity, 100 shares at $100 becoming 200 shares at $50 right after a two-for-one split. In a journal, a position opened before the split and closed after it has to be corrected in quantity and price, or it shows a loss that never happened.
This factor matters particularly for traders using stock options, where dividend dates can influence contract valuation and sometimes trigger early exercise on short positions: according to a Cboe note on dividends and short trades, when a call is in the money going into the ex-dividend date and the dividend exceeds the remaining time value, its owner has an incentive to exercise early, and the seller then has to deliver the shares as well as the dividend. Even for a purely stock trader with no options, keeping these dates in mind avoids misreading a mechanical move as a market signal.
Liquidity, very uneven from one stock to another
Unlike major forex pairs or the most-traded futures, liquidity varies enormously from one stock to another. A large-cap trades with a tight spread and comfortable market depth, while a small-cap can have a wide spread and a thin order book, making execution far more costly in practice than the price chart alone suggests. The SEC's guide to microcap stocks, companies with a market capitalization below $250 or $300 million in its typical definition, notes that these stocks tend to be low priced and trade in low volumes.
A stock journal benefits from noting the market cap or liquidity category of the ticker traded, to check whether part of an underperformance comes from poorly anticipated execution cost on less liquid names, rather than an analysis error. It's an easy factor to overlook, and it can explain the gap between a setup's theoretical performance on paper and its real result once executed. Fees and taxes belong in the same calculation: in France, buying shares of a French company whose market capitalization exceeds one billion euros bears the financial transaction tax, a condition set in the tax's scope in the official bulletin of public finances, and the same bulletin's update of May 28, 2025 raises its rate to 0.4% for purchases made from April 1, 2025. It never shows on the chart, it shows on the statement.
Watchlist size, a dispersion factor
The stock market offers a nearly unlimited choice of tickers, which pushes you to keep expanding your watchlist, with the idea that more monitored opportunities means more trades taken and therefore more gains. Trading more has a measured cost, though: across 66,465 households with accounts at a large US discount broker from 1991 to 1996, Barber and Odean's study “Trading Is Hazardous to Your Wealth” measures an annual return of 11.4% for those who traded most, against 17.9% for the market, with the average household turning over 75% of its portfolio each year. These are individuals invested in US stocks, not day traders, and the study doesn't measure watchlist size; it only recalls that every order has a cost. A ticker added to the list also means a less fine-grained read of its usual behavior, key levels and reaction to news.
Tracking in your journal the number of different tickers traded over a given period, and crossing that figure with your performance, can reveal a tipping point: past a certain number of actively followed tickers, win rate degrades, a sign the watchlist grew faster than the real capacity to know each ticker well. Deliberately trimming the list after seeing it in your own numbers is a simple decision, and it changes nothing about the analysis method itself.
Day trading, swing and position: horizons not to mix
The stock market lends itself to very different holding horizons, from day trading that closes everything before the session ends, to swing trading that holds a position for several days, up to position trading that can stretch over several weeks or months. Each horizon follows a different risk logic: day trading avoids overnight gap risk, while swing and position trading accept it in exchange for a potentially larger move.
Mixing these horizons in the same statistics, without distinguishing them with an explicit tag, prevents you from knowing which one truly constitutes your edge. A trader might, for example, have an excellent win rate in swing trading but a neutral or negative result in day trading on the same tickers, a critical piece of information for directing time and energy, but one that stays invisible as long as the journal doesn't separate the two approaches. The tag also guards against a well-known drift: the losing day trade kept “as a swing”, then “as a position”, for want of accepting the loss. Across 10,000 accounts at a large US discount brokerage from 1987 to 1993, Terrance Odean's study of the disposition effect shows that these investors realized their gains far more readily than their losses. A horizon logged at entry, and never changed afterward, makes that drift visible in your own numbers.
How Tradoshi helps with your stock journal
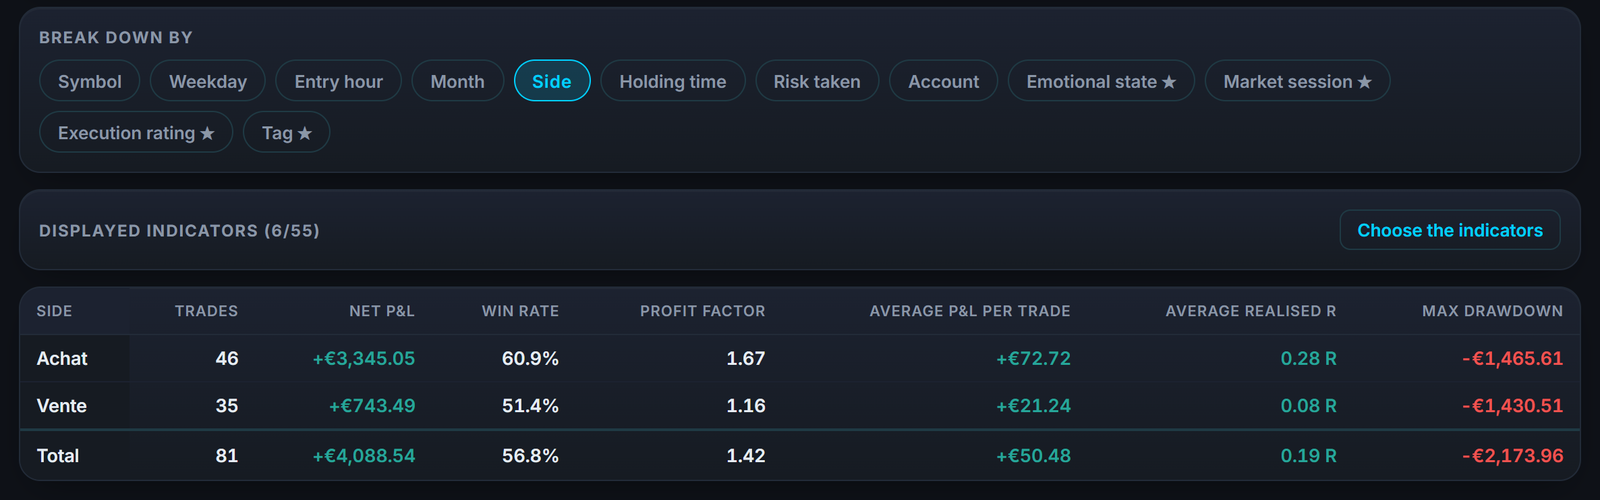
Tradoshi centralizes your stock trades with a journal that lets you tag the context specific to each trade, sector, earnings window, horizon, or any other category useful for your analysis, to reveal where your edge really lives rather than drowning it in a general average. Writing it down matters: in the meta-analysis by Harkin and colleagues published in 2016 in the Psychological Bulletin, across 138 studies and 19,951 participants, monitoring progress promoted goal attainment (d+ = 0.40), more so when the information was physically recorded; those were health and habit goals, not trading.
- Universal CSV import compatible with most stock brokers.
- Customizable tags to categorize sector, earnings window, or any other context.
- Per-tag statistics to compare your performance across categories.
- R-multiple and expectancy to judge your edge independently of position size.
Frequently asked questions
Why tag trades taken around earnings announcements?
Because an earnings announcement can trigger an opening gap that jumps straight over your stop, a completely different risk profile from a classic technical trade. Blending these two categories in the same statistics distorts the read of your real edge on each.
What's the point of sector tagging in a stock journal?
It reveals whether your edge is truly generalist or concentrated in one or two sectors. It also lets you spot hidden correlation between several positions in the same sector, which can move together on sector news and turn an apparently diversified bet into one concentrated bet.
What is the pattern day trader rule?
In the US, it designated as a pattern day trader any margin account customer who executed four or more round-trips within five business days, and required them to keep at least $25,000, or the broker restricted their day trading. FINRA replaced it on June 4, 2026 with an intraday margin standard that has no $25,000 minimum; brokers have until October 20, 2027 to switch, and until yours has, it may still apply the old rule.
Do dividend dates actually matter?
It's a minor but real factor: on the ex-date, whoever buys no longer receives the dividend and the price may fall by its amount, a move unrelated to technical analysis. It's particularly relevant for stock options traders, where these dates can influence contract valuation.
Why track a stock's liquidity in my journal?
Because it varies enormously from one stock to another. A less liquid ticker has a wider spread and a thinner order book, making execution more costly than the chart alone suggests. Noting the liquidity category helps distinguish underperformance due to execution from underperformance due to analysis.
How does Tradoshi help analyze my stock trades by context?
Through customizable tags (sector, earnings window, or any other useful category) and statistics computed per tag, to compare your performance across categories and reveal where your edge really lives rather than drowning it in a general average.
Should I limit the number of tickers on my watchlist?
It's a serious lead. A trader who follows around ten tickers can develop a fine-grained read of their usual behavior, while a very broad watchlist dilutes that knowledge. Crossing the number of tickers traded with your performance in your journal can reveal a tipping point past which win rate degrades.
Should I separate day trading, swing and position trading in my journal?
Yes. These horizons follow different risk logics, notably around overnight gap risk. Mixing them without an explicit tag prevents you from knowing which one truly constitutes your edge, since a trader might perform well in swing but not in day trading on the same tickers.
What if my trades around earnings are consistently losing?
That's valuable information, not a failure to ignore. If the tag reveals a clear underperformance in that specific category, the most profitable decision is often simply to exclude positions opened near an earnings announcement, rather than keep searching for a technical fix that won't correct a problem of a different nature.
Does trading stock options require an even different journal?
Yes, to some extent. Beyond the underlying's price, an options position adds variables of its own like the expiration date, implied volatility at the time of opening, and the time-decay sensitivity that erodes an option's value as it nears expiration. A trader combining stocks and options benefits from separating these two categories in their journal, given how differently their risk mechanics work. For the money side of a closed contract, the call and put profit calculator turns the strike, the premium paid and the price at expiration into a net result and a breakeven.
Should I account for market cap when analyzing my trades?
Yes, alongside the sector tag. A small cap can react disproportionately to minor news, while a large cap generally absorbs that kind of information better. Crossing market cap with trade results helps you understand whether your edge depends on a specific company size rather than an entire sector, a distinction that a sector tag alone won't always surface on its own.