 By Benjamin Roure L'Hermitte
A trading edge is a measurable statistical advantage: if you repeat your trades a large number of times, you make money on average. It isn't a secret, a magic indicator or a gut feeling, and it is proven with numbers, not with an impression. This guide explains what an edge really is, how to know whether you have one, and how to protect it once you've found it.
- An edge is a statistical advantage: over a large number of trades, your system wins on average.
- It's measured, not felt: expectancy and profit factor tell you whether your edge is real.
- A good edge can have a low win rate: what matters is the ratio between your gains and losses.
- Your execution can destroy a real edge: discipline turns a theoretical advantage into concrete gains.
Looking for an edge in the wrong direction is easy: piling up indicators, changing strategy every month, mistaking a good streak for a real advantage. The result: you never know whether you're winning through skill or luck, and you abandon a profitable method at the first drawdown.
An edge is neither complicated nor mystical. It's simply the fact that, if you repeated your trades hundreds of times under the same conditions, the sum of your results would be positive. This guide shows you how to define your edge, measure it honestly, and above all how to avoid destroying it yourself once you have it.
What an edge really is
An edge, in trading, is a statistical advantage: a mathematical reason to believe that, by repeating your process a large number of times, you'll end up in the green. It's not a guarantee of winning the next trade, or even the next ten. It's a positive expectancy over the long term, exactly like the casino has an edge on every spin of the roulette wheel without knowing who will win the next round.
This casino analogy is the best way to understand an edge. The casino doesn't know whether the next player will win or lose, and it doesn't care: it knows that over millions of spins, the odds work in its favor, and the law of large numbers does the rest. A trader with an edge is in the same position: they lose individual trades without a problem, because they know that repeating their process makes them a winner on average.
The two ingredients of an edge
An edge always rests on two parameters, and one alone is never enough. The first is your win frequency, your win rate: the proportion of your trades that end up winning. The second is your gain/loss ratio: how much you win on average on your winning trades compared to what you lose on your losing ones. These two numbers combine to determine whether your system has a positive or negative expectancy.
| System profile | Win rate | Gain/loss ratio | Edge? |
|---|---|---|---|
| Trend follower | 35% | 3.0 | Yes, rare big gains |
| Tight scalping | 65% | 0.7 | Yes, small frequent gains |
| Classic trap | 70% | 0.3 | No, rare losses erase everything |
| Beginner's illusion | 50% | 1.0 | No, zero margin |
This table shows why a high win rate means nothing on its own. A system that wins 70% of the time but whose losses are more than three times bigger than its gains is a loser. Conversely, a system that wins only a little over a third of its trades can be excellent if its winners pay big. The arithmetic, in multiples of the risk taken per trade: 0.35 × 3 − 0.65 = +0.40 R for the trend follower, 0.65 × 0.7 − 0.35 = +0.105 R for tight scalping, 0.70 × 0.3 − 0.30 = −0.09 R for the classic trap, and zero at 50% with a ratio of 1, before costs. It's the combination of the two parameters that creates, or destroys, your edge. You can see where your own pair lands by calculating your win rate next to the threshold your gain/loss ratio demands.
Measuring your edge: expectancy
The cleanest way to summarize an edge in a single number is called expectancy. It answers a simple question: how much does each of your trades return, on average? In the Van Tharp Institute's trading concepts, R is the initial risk of a trade, each result is written as a multiple of that risk, and expectancy is the mean of those multiples. If the result is positive, you have an edge; if it's negative, your system costs you money on every trade, on average.
Expectancy is powerful because it turns an emotional question ('am I any good?') into a cold, actionable number. Expressed in units of risk (in R), it tells you your advantage per trade independent of your position size. An expectancy of +0.3 R means each trade returns on average 30% of your risk: with $100 risked per trade and 200 trades in the year, the expected result is 0.3 × 100 × 200 = $6,000. That is an average, around which your actual result will vary.
Van Tharp uses this vocabulary, R and expectancy, throughout his books, including the one we present among the best trading psychology books.
An edge isn't felt, it's computed. Until you can put a number on your advantage, you don't know whether you have a skill or just a good streak.
Profit factor, the other judge
Alongside expectancy, the profit factor is the most useful indicator for judging an edge. The MetaTrader 5 help page on the testing report defines it as the ratio of the gross profit to the gross loss, and adds that a value of one means the two are equal. Above 1, you win more than you lose; below, the opposite. A profit factor of 1.5 means that for every unit lost, you win one and a half.
The profit factor has the advantage of being immediately meaningful, but it is only worth the sample behind it. A system that has strung together ten wins can look brilliant, but if its profit factor over a hundred trades is 1.05, it earns only 5 cents per unit lost: the margin is thin and a bad run can send it below 1. Looking at the profit factor over a large sample, and not just your last few trades, protects you from the illusion of competence.
How many trades to prove an edge
The number-one trap is concluding too fast. Over ten trades, anyone can be a winner or a loser by pure chance: a system with no advantage at all, winning one time in two, strings together at least seven winners out of ten in 17% of cases, roughly one time in six. The sample is far too small to distinguish skill from luck. It's the law of large numbers that makes an edge emerge, and it needs volume to speak. As long as your sample is small, your results are dominated by noise, not by your advantage.
There's no magic threshold, but there are two benchmarks. The Van Tharp Institute asks for at least thirty trades to get a first idea of your expectancy, and rather a hundred to two hundred for a clear picture. And the confidence interval calculation, as set out in the NIST statistics handbook, from the US standards institute, shows what a measured win rate is worth: 60% over 30 trades sits, at 95% confidence, between roughly 42% and 75%; over 100 trades, between 50% and 69%; over 400 trades, between 55% and 65%. With a gain/loss ratio of 1, breakeven is at 50%: so it takes about a hundred trades just to begin ruling it out. That's why a patient journal, accumulating hundreds of trades, is the only serious way to know whether your edge is real or imaginary.
The difference between an edge and luck shows over time: luck does not repeat from one year to the next. The study by Barber, Lee, Liu and Odean of stock day traders in Taiwan, from 1992 to 2006, measured it. In the average year, about 360,000 individuals day trade there and about 13% earn profits net of fees; but those who still reliably beat the market the following year, after costs, number about 1,000, less than 1%. One good year therefore does not prove an edge, its repetition begins to. These figures hold for that market and that period, not for forex or futures. The question that follows, is day trading gambling or skill, has its own article.
Statistical edge vs execution edge
We often talk about the edge as if it were only the strategy, but there are really two distinct edges. The first is the statistical edge: the intrinsic quality of your system, measured on paper or in backtest. The second is the execution edge: your ability to apply that system in reality, without sabotaging it through fear, greed or impatience.
This is a crucial distinction, because a real statistical edge can be destroyed in execution: cutting gains too early, letting losses run, skipping planned trades and taking off-plan ones. The first of these habits is documented: across 10,000 accounts at a US discount broker, from 1987 to 1993, Terrance Odean's study of the disposition effect shows stock investors realizing their gains more readily than their losses. The system wins on paper, but the hand loses on the account. An edge only truly exists when your discipline turns it into results, which shifts the real work toward your behavior.
Why an edge erodes
An edge isn't eternal. Markets change, the conditions that made your strategy a winner can disappear, and an advantage everyone knows about tends to close. Research has measured it on stocks: in McLean and Pontiff's 2016 study in the Journal of Finance, the return of 97 variables shown to predict stock returns is 26% lower out of the original sample, and 58% lower after publication. That's why an edge must be monitored over time, not simply discovered once and forgotten. A system that worked two years ago may have become neutral today without you noticing.
The only way to detect the erosion of an edge is to track your statistics continuously. If your expectancy and profit factor steadily degrade over several months, it's probably not bad luck: it's the sign that your edge is weakening and needs to be adjusted or rebuilt. Without a journal, you'll only see this decline once your account has already suffered.
How to find your own edge
An edge is easier to find by specializing than by chasing the perfect indicator. A single setup, a single market, a single time window: it is also the fastest way to accumulate enough comparable trades to measure anything. Better one precise setup measured over two hundred trades than ten setups measured over twenty trades each. Depth beats breadth.
Concretely, you find your edge by observing your own data. Which setup pays you the most? What time do you win? On which instrument? These answers don't come from your intuition, they come from your journal. By segmenting your trades by setup, time and market, you see the places where your advantage is real emerge, and those where you lose money without knowing it. Your edge is already in your numbers, it just needs to be revealed.
The role of position sizing in your edge
Your edge is measured without regard to your position size, but size decides whether it is ever realized. Two traders with the exact same statistical system can have opposite trajectories depending on their money management. Risking too much on each trade, even with a real edge, exposes you to a risk of ruin that can knock you out of the game before the law of large numbers has time to work in your favor. An edge of +0.3 R per trade is useless if a normal, mathematically expected losing streak blows up your account before you reach the number of trades needed for that advantage to materialize.
Conversely, an overly cautious size dilutes a real edge to the point of making it insignificant. The right calibration sits between the two: enough risk for your edge to produce meaningful growth, little enough to survive the losing streaks your system, however excellent, will inevitably face. Concrete example: a trader who risks 1% of their capital per trade and takes ten consecutive losses, a streak that is rare but possible even with a good system, loses a little under 10% of their account, and a gain of about 11% brings them back to where they started. The same trader risking 5% per trade would lose 40% of their account, and would then need a 67% gain to get back to where they started. Your money management doesn't create your edge, but it determines whether you'll live long enough to benefit from it.
The mistakes that make you believe in an edge that doesn't exist
A few classic mistakes create the illusion of an edge where none exists. The first is ignoring costs: spread, commissions, overnight financing. A system that looks slightly positive gross can turn negative net once these costs are factored in, especially on high-frequency strategies where every fee counts. Counting only the result shown on your statement, without checking it truly includes all fees, systematically makes you overestimate your real edge.
The second mistake is confusing correlation with edge: noticing that 'every time I see X, the market does Y' over a handful of occurrences establishes nothing statistically solid. It is easy to see a pattern where there is only a coincidence, and a small number of favorable coincidences is enough to create a conviction the sample does not justify. The third mistake, more insidious, is blending several edges without distinguishing them: if you trade three different setups and look at the combined result, one winning setup can mask a losing one. Always separate your statistics by configuration, or you risk keeping a bad setup alive simply because the overall result stays positive.
The same caution applies to public data said to show what the large players are doing. The Commitment of Traders report, for example, describes positions that are three days old: until you have measured what it changes in your own trades, it is not an edge.
How Tradoshi helps you measure your edge
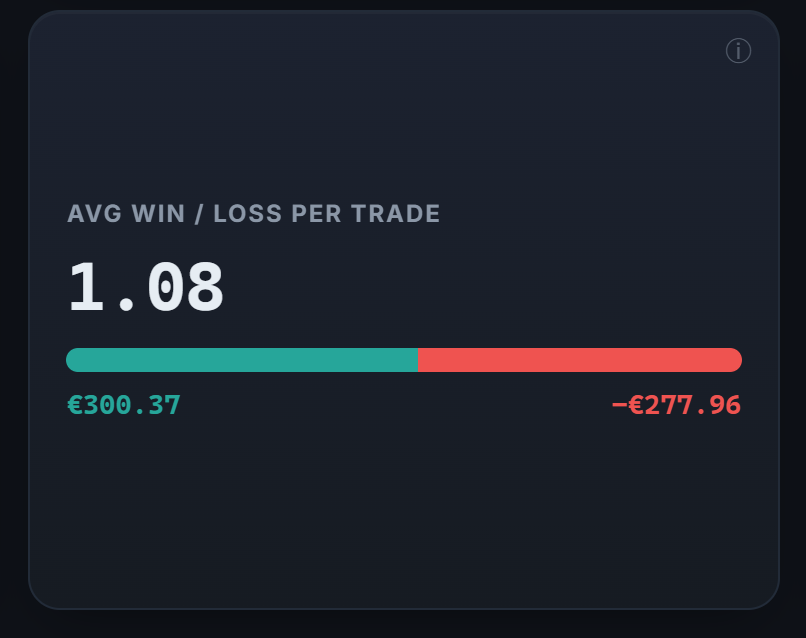
Tradoshi computes your edge automatically from your real trades: your expectancy, your profit factor, your average R-multiple and your gain/loss distribution, without you doing a single calculation. You finally see, with the numbers to prove it, whether your advantage is real and where it hides.
- Expectancy and profit factor computed over all your trades, to judge your edge at a glance.
- Breakdowns by instrument, hour and day to spot where your advantage is strongest.
- Tracking over time to detect the erosion of an edge before it gets expensive.
- Discipline score to check that your execution edge isn't destroying your statistical edge.
Three trading-floor expressions worth understanding
The pain trade is the move that hurts the largest number of participants at once. It is not a conspiracy theory: when a position is widely shared, the exit is narrow, and the path of least resistance becomes the one that dislodges the most people. The image comes from Edwin Lefèvre's book modelled on Jesse Livermore, Reminiscences of a Stock Operator (1923), which speaks of the 'line of least resistance': the direction in which price moves most easily, which the speculator waits to see define itself before acting. Knowing it does not help you predict, but it stops you being surprised.
A market structure shift is the moment the sequence of highs and lows inverts. What is a market shift, then? The first objective signal that a trend has stopped, ahead of any pattern and any indicator. In the same vocabulary, trailing down describes a limit that tightens session after session, not a price move.
The 80/20 trading strategy applies Pareto's rule to your own results: the idea that a minority of your setups produces most of what you earn. It is a hypothesis to check, not a law, and only your journal says whether it holds for you. The practical consequence is unpleasant and simple: some of the ideas you test deserve to be dropped, and the journal is the only place where you can decide which ones without lying to yourself. In day trading, inversions, where a level that acted as support starts acting as resistance, are one setup worth putting through that test.
One point of schedule, often misunderstood: do futures trade 24/7? Not quite. Sessions run almost around the clock, but from Sunday evening to Friday evening, with a daily break.
Frequently asked questions
What is an edge in trading?
It's a statistical advantage: a mathematical reason to believe that, by repeating your process a large number of times, you'll make money on average. It's not a guarantee on the next trade, but a positive expectancy over the long term, like the casino has an edge on every spin without knowing who will win the next round.
How do I know if I have an edge?
By measuring your expectancy (your average gain per trade) and your profit factor (your total gains divided by your total losses) over a large sample of trades. If both are positive and stable over dozens or hundreds of trades, your edge is probably real. Over ten trades, your results are just noise.
Does an edge need a high win rate?
No. A system can win only a third of its trades and be excellent if its winners pay far more than its losers cost. Conversely, a 70% win rate can be a loser if the rare losses are huge. It's the combination of win rate and gain/loss ratio that creates the edge, not the win rate alone.
How many trades does it take to prove an edge?
There's no magic threshold. The Van Tharp Institute gives as a benchmark at least thirty trades for a first idea, and rather a hundred to two hundred for a clear picture. A 60% win rate measured over 100 trades still sits, at 95% confidence, between roughly 50% and 69%. A journal that accumulates hundreds of trades is the only serious way to distinguish skill from luck.
Why can an edge disappear?
Because markets change, the conditions that made your strategy a winner can fade, and an advantage exploited by too many people closes. An edge must be monitored continuously: if your expectancy and profit factor degrade over several months, it's probably the sign that your edge is weakening and needs adjusting.
How do I find my own edge?
By specializing rather than hunting for the perfect indicator, and by observing your own data. Segment your trades by setup, hour and instrument to see where your advantage is real. Your edge is already in your journal: you just need to reveal it with statistics, instead of guessing it.
Is money management part of the edge?
Indirectly, yes. A statistical edge exists independently of position size, but your size determines whether you'll survive long enough to benefit from it. Risking too much on each trade exposes you to a risk of ruin that can knock you out before the law of large numbers works in your favor, even with a real edge. Proper calibration protects your edge, it doesn't create it.
Can you have several edges at the same time?
Yes, as long as you measure them separately. If you trade several setups and only look at the combined result, one winning setup can mask a losing one. Always separate your statistics by configuration: it's the only way to know which of your edges is real and which is quietly costing you money.