 By Benjamin Roure L'Hermitte
The daily loss limit is the maximum amount a prop firm account can lose within a single trading day. What happens when you hit it depends on your firm: at some, it is a rule violation; at others, your positions are closed and you resume at the next session. Reading that rule as your firm writes it, then setting a margin below it, is what this guide is for.
- The consequence depends on the firm: hitting it is a rule violation at some, and simply the end of your session at others.
- Its threshold is set for the day: a fixed amount, or a percentage subtracted from the balance recorded at a set time.
- Floating P&L counts: an open losing position can breach the limit in real time.
- The counter is a daily risk budget deliberately below the official limit.
When you discover prop firms, you focus on the profit target. The loss rules deserve the same attention, starting with the one that plays out over a single day. On Topstep's help page on its Daily Loss Limit, read in October 2026, the company writes that over 63% of traders have lost an account in a single day, without stating the period or the method behind that figure. It only holds for that company, but it shows the scale at which the risk plays out: the session.
The trap is trading under this limit without knowing how it's computed, forgetting that floating P&L counts, or not knowing the time at which its threshold is reset. This guide explains how the daily loss limit works according to the official pages of two firms, where the differences from one firm to the next lie, and how to build a daily risk budget that keeps you well away from the threshold.
What the daily loss limit is
The daily loss limit is the maximum amount an account can lose in a single trading day. It's expressed as a percentage of capital or as a fixed amount. According to FTMO's page on its trading objectives, read in October 2026, it is 3% of the initial capital on the 1-Step model and 5% on the 2-Step model. According to Topstep's help page, read the same month, it is $1,000 on a $50,000 account, $2,000 on $100,000 and $3,000 on $150,000. Unlike the maximum loss, which runs across the whole life of the account, this one starts each day from a fresh threshold. These figures change: reread your firm's page before relying on them.
It's a risk management rule set by the prop firm: Topstep presents it as the way to make sure one bad day doesn't wipe out the account. Its exact mechanics vary from firm to firm, and those differences are what you need to read in detail, like the other criteria for choosing your prop firm. Never assume: reading precisely how your firm computes this limit is the first step. Some firms publish these rules in a separate FAQ or PDF rather than in the main terms: take the time to find and read it before risking a single dollar.
How it's computed (the trap)
The first thing to read is the calculation base, and it isn't the same everywhere. At FTMO, according to its page, the day's threshold is recalculated every day at midnight Central European time: it is the account balance recorded at that moment, minus the daily loss amount (3% or 5% of the initial capital depending on the model). That threshold then stays in force until the following midnight. At Topstep, according to its page, the limit is a fixed dollar amount chosen when the account is purchased, and the day's net P&L is what gets compared to it. In both cases the threshold does not move during the session: it is the monitoring that happens in real time. Topstep also offers, as an optional personal setting, a trailing limit that rises with the balance and never moves back down.
| Calculation base | What it implies |
|---|---|
| Fixed dollar amount (Topstep) | The same every session: $1,000 on a $50,000 account |
| Balance recorded at midnight, minus a percentage of initial capital (FTMO) | The day's threshold depends on the previous evening's balance |
| Trailing personal limit (optional setting at Topstep) | The threshold rises with your balance and never moves back down |
The other thing to read is floating P&L. The limit doesn't only trigger on your realized losses. At FTMO, the page defines the monitored equity as the balance plus the P&L of open positions, swaps and commissions included: if it drops below the threshold, the rule is considered violated. At Topstep, the daily limit is compared to the day's net P&L, and Topstep's page on its Maximum Loss Limit states that this other limit is hit including on unrealized P&L. Holding a losing position while hoping for a reversal therefore doesn't shelter you: your equity can cross the line before you have cut anything.
Why a bad day leads straight to the limit
The daily loss limit strikes where emotion is strongest: in a bad day. That behaviour has been measured among professionals: according to Coval and Shumway's study in the Journal of Finance (2005), Chicago Board of Trade proprietary traders who lose in the morning are about 16 percent more likely to take above-average risk in the afternoon than those with morning gains. That result is about those traders, not about someone taking a challenge, but it describes the slope: when you're losing, the urge to win it back rises, you increase size, you multiply trades. The rule meant to protect you becomes the wall your revenge trading sends you into.
It isn't the daily limit that fails traders. It's their inability to stop before reaching it.
The disciplined trader doesn't approach the official limit, because they set their own limit well before. The firm says 'you can lose 5% today'; they hear 'I stop at 2%'. That safety margin doesn't guarantee passing an evaluation, but it takes off the table the one day that would be enough to lose it.
The counter: your daily risk budget
The solution is to never use the firm's limit as your limit. Set a deliberately lower daily risk budget, and treat it as your true red line. If the firm allows 5% loss per day, decide you stop at 2 or 3%. That margin protects you from surprises (floating P&L, spread, execution) and above all from yourself in a bad patch. On your own account, outside a prop firm, the logic is the same: our guide to risk management in day trading shows how to fit that budget to the number of trades you take in a session.
- Read precisely how your firm computes the daily limit (base and floating P&L).
- Set your daily budget at half or less of the official limit.
- Translate that budget into a number of trades: at 1% per trade and 3% budget, you stop after 3 losses.
- Monitor your equity in real time, floating P&L included, not just your realized losses.
- Stop dead as soon as your daily budget is reached, no negotiation.
This daily budget connects directly to your stop-after-X-losses rule: both protect the same thing, your survival in a bad day. Combining them puts two stops ahead of the official limit, and you would have to break both to reach it.
Daily limit and time zones
A detail not to overlook: the exact time your daily limit starts over. Each firm defines its own trading day. At FTMO, according to its page, the threshold is recalculated at midnight Central European time (CET or CEST depending on the season). At Topstep, according to its page, the trading day runs from 5 PM to 3:10 PM Chicago time (CT), and an account whose limit has been hit cannot open a new trade before 5 PM. If you don't know this moment, you can think you're starting a new day when you're still in the old one, or the reverse.
This point becomes critical if you trade around the day rollover or hold positions overnight. At FTMO, for example, the threshold is computed from the balance recorded at midnight, so without the P&L of positions still open, whereas it is equity, open positions included, that is monitored: a floating loss at midnight already eats into the next day's room. The rule is always the same: read precisely how and at what time your firm defines its day, and adapt your trading accordingly.
Daily limit and position size
The daily loss limit directly determines the maximum size you can afford, and that can be calculated. If your limit is 5% and you want to be able to absorb at least three losses before reaching it, each loss must stay under 5 ÷ 3 = 1.67% of your capital, so 1.6% at most. With a 3% limit, the same calculation gives less than 1% per trade. Reasoning backward, from the daily limit to the size per trade, is the right method: you start from what you must not exceed and derive how much to risk per position.
This logic spares you the too-big-size trap, where one or two losses are enough to blow your day. By sizing your positions to absorb a normal losing streak without reaching the limit, you give yourself the margin needed to let your edge express itself. A trader who computes their size from their daily limit knows how many losses they can take in the session; one who takes big positions without this calculation finds out along the way.
Emotional discipline facing the limit
The daily limit tests your psychology as much as your management. As you near the limit, two opposite and both dangerous reactions lurk. The first is panic: you tense up, cut your good trades too early, become unable to trade normally for fear of crossing the line. The second is denial: you ignore that you're approaching the limit and continue as if nothing were happening, until you cross it inadvertently.
The right attitude is between the two: a calm awareness of your situation. You know exactly where you stand relative to your limit, you adapt your behavior accordingly (slow down, reduce, stop as the case may be), without panicking or denying. This quiet clarity isn't improvised: it comes from having decided your budget in advance and tracking your position in real time. When you know precisely where you stand, the limit stops being an anxiety-inducing threat and becomes a simple marker you manage with composure.
Common mistakes with the daily limit
Certain mistakes lead straight to this limit. The first is moving your stop to avoid locking in a loss, hoping for a reversal, even though floating P&L already counts toward the limit: you gain nothing by delaying the inevitable, you simply take on more risk while your equity keeps sliding. The second is stacking small entries after a loss to 'make up for it' psychologically: each new position adds net risk exactly when you should be cutting it instead.
Another classic mistake, more subtle, is forgetting the cost of spread and slippage in your margin calculation. Near the limit, a few extra points of execution slippage can be enough to tip you over, especially on volatile instruments or outside high-liquidity hours. Finally, if you manage several accounts across different firms, never assume the rules are identical: according to their pages, FTMO subtracts a percentage from the balance recorded at midnight while Topstep applies a fixed dollar amount, and the consequence of a breach is not the same. Applying one account's rules to another is carelessness, not lack of skill, and it is prevented by writing each account's rules down in black and white.
A worked example: building your safety margin
Take a purely illustrative example to make the method concrete. Imagine a $50,000 evaluation account with a 5% daily loss limit: 50,000 × 5% = $2,500. Instead of using that figure as your reference, you set your personal budget at 2%: 50,000 × 2% = $1,000. With 1% risk per trade ($500), your budget leaves you 1,000 ÷ 500 = 2 losses before you stop, and there is then $1,500 left between you and the firm's limit.
This simple calculation, done once in a calm moment, becomes your reference for every session: two consecutive losses, you close the platform, whatever setup shows up next. The point of this exercise isn't the exact number, which depends on your account and your firm, it's the method: start from the official limit, apply a deliberate safety margin, and derive a concrete number of trades you can count on your fingers mid-session, without doing mental math under pressure.
The same calculation with published figures, taken from the two firms' pages in October 2026. On a $100,000 FTMO 2-Step account, the daily loss is 100,000 × 5% = $5,000: on day one, the threshold sits at $95,000. A personal budget of half that is $2,500, or 2,500 ÷ 500 = 5 losses at 0.5% per trade. Floating P&L changes the count: if you go through midnight with a $100,000 balance and an open position showing a $1,000 floating loss, the next day's threshold stays at $95,000 but your equity starts from $99,000, and your real room is down to $4,000. On a $50,000 Topstep account, the optional Daily Loss Limit is $1,000 and the Maximum Loss Limit is $2,000: two days stopped at the limit, with no gain in between, use up 2 × 1,000 = $2,000, the whole maximum loss.
The daily limit and news volatility
High-impact macro announcements (jobs data, rate decisions, central bank speeches) are an aggravating factor often left out of your safety-margin calculation. In the US Treasury market, Fleming and Remolona's study for the Federal Reserve Bank of New York observes that the bid-ask spread widens dramatically with price volatility around major announcements. On your market the practical consequence is the same: a normally sized position can inflict a bigger loss than expected if it's still open at the moment of the release.
The fix is simple: reduce your size or skip trading entirely in the minutes around a high-impact announcement, and close any open position before the release time if you're not certain you want to carry that risk. That's not excessive caution, it's a rational adjustment: your usual safety margin assumes normal execution, and news volatility falls precisely outside that assumption. A risk budget respected on paper can in that way be exceeded at execution.
Take the theoretical example of a trader holding an open position through the release of the US jobs report (NFP). Their stop sits 20 pips away for a 1% risk. If it is filled 35 pips away because of slippage, the loss becomes 1 × 35 ÷ 20 = 1.75%; at 40 pips, it reaches 2%. Repeated a few times, this single factor can be enough to blow a risk budget that was otherwise well calculated under normal conditions.
Tracking it with Tradoshi
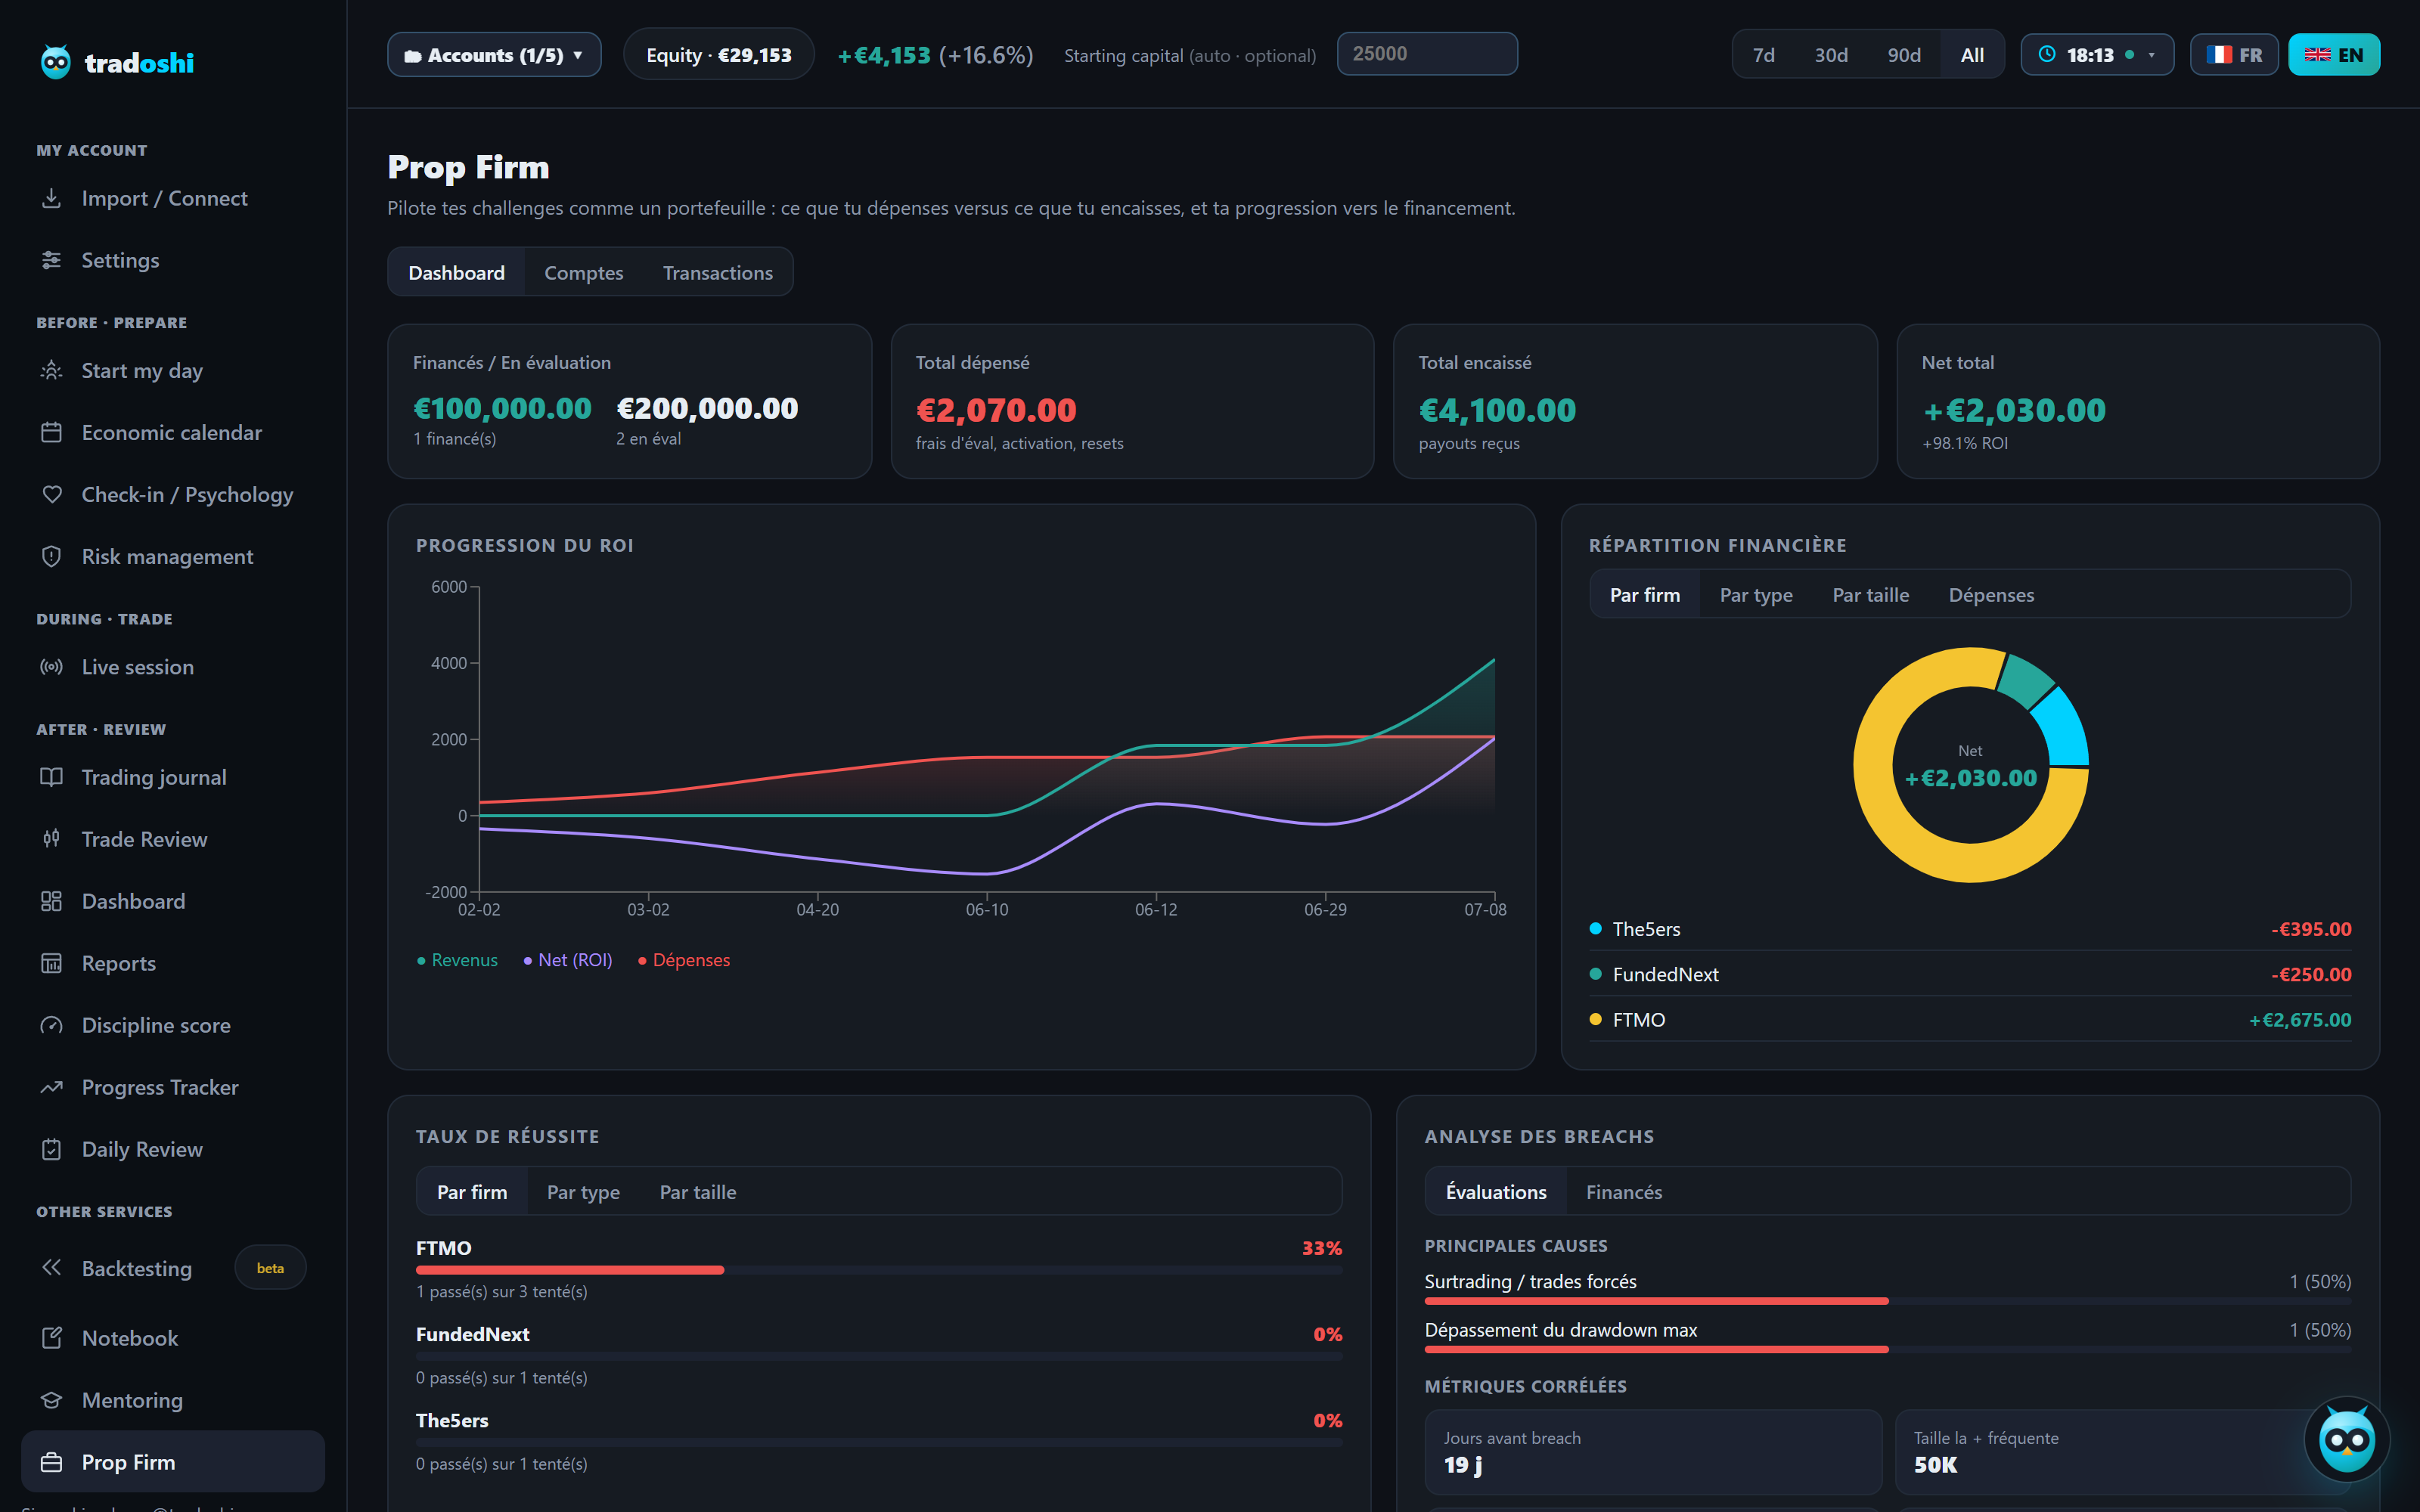
Tradoshi knows your funded accounts' rules and tracks your drawdown in real time, so you see at every moment where you stand relative to your daily limit and your own risk budget.
- Drawdown tracked continuously: your day's loss is computed in real time, floating P&L included.
- Prop firm rules: your daily and total limits are tracked against your real performance.
- Daily budget: your personal stop threshold is measured on every trading day.
- Proximity alert: days where you near your limits stand out in your stats.
Frequently asked questions
What is the daily loss limit in a prop firm?
It's the maximum a prop firm account can lose in a single trading day, expressed as a percentage of capital or as a fixed amount. Unlike the maximum loss, its threshold starts over each day. The consequence of a breach depends on the firm: a rule violation at some, simply the end of the session at others. Read your own firm's official page.
How is the daily limit computed?
It depends on the firm. According to their official pages read in October 2026, FTMO subtracts every day at midnight Central European time 3% or 5% of the initial capital (depending on the model) from the balance recorded at that moment, and Topstep applies a fixed dollar amount per account size. In both cases the threshold is set for the day and monitored in real time. Read your firm's rules precisely, never assume.
Does floating P&L count toward the daily limit?
Yes in both rulebooks read for this guide. FTMO monitors equity, meaning the balance plus the P&L of open positions, and Topstep compares its limit to the day's net P&L. An open position that dives can therefore take you through the threshold before you have cut anything. Check this point in your own firm's rules.
Why does this rule trigger on bad days?
Because it strikes where emotion is strongest. When you lose, the urge to win it back rises, you increase size and multiply trades. A study published in the Journal of Finance in 2005 measured this behaviour among professional traders in Chicago: those who lose in the morning more often take above-average risk in the afternoon. The rule meant to protect you becomes the wall your revenge trading sends you into.
How do I avoid exceeding the daily limit?
Never use it as your limit. Set a deliberately lower daily risk budget (say half) and treat it as your true red line. Translate it into a number of trades, monitor your equity in real time including floating P&L, and stop dead once reached. That margin shields you from surprises and from yourself.
What daily risk budget should I target in a prop firm?
A budget of about half the official limit is a good benchmark: if the firm allows 5% loss per day, stop at 2 or 3%. Combined with 1% risk per trade, that means stopping after 2 or 3 losses. That margin leaves you room for floating P&L, spread and execution.
What should I do if I'm close to my daily limit?
Stop before you reach it, not after. If you're nearing your personal budget (which should already sit below the official limit), close the platform rather than attempt one last trade to win it back. Getting close to the limit is already a sign your day is emotionally compromised; staying exposed only raises the risk of an accidental breach through floating P&L.
Are daily loss rules the same across all prop firms?
No, and that's something to check if you manage several accounts. According to their official pages, FTMO computes a threshold from the balance recorded at midnight and treats a breach as a rule violation, whereas Topstep applies a fixed amount and states that hitting it is not a violation. Never assume one account works like another: check each firm's rules, separately, before you trade.