 By Benjamin Roure L'Hermitte
Analyzing your trading performance means breaking your result down into its causes: measuring a few indicators (win rate, profit factor, expectancy, drawdown, average R), then splitting them by time, instrument and setup to understand where your gains and losses really come from. Looking at your P&L isn't enough: it gives the total, not the explanation. This guide explains how to run that analysis completely and usefully, with the definitions and the studies it rests on.
- Analyzing isn't looking at your P&L: it's understanding where your results come from.
- A few key indicators suffice: win rate, profit factor, expectancy, drawdown, average R.
- Breakdowns reveal the why: by time, instrument, setup and emotion.
- Analysis leads to action: repeat what works, cut what loses.
Looking at your balance and analyzing your performance are two different things. The balance tells you where you stand, but nothing about why. To progress, you need to understand the causes of your results: which indicators reveal your trading's health, where your gains come from, where your leaks are. This understanding separates the trader who improves from the one who repeats the same mistakes.
Analyzing your performance isn't reserved for professionals and doesn't require complex spreadsheets. With a handful of well-chosen indicators and a few relevant breakdowns, you get a clear picture of your trading. This guide gives you the method: which indicators to watch, how to interpret them, and how to turn this analysis into concrete decisions. It all starts with the raw material: without trades recorded properly there is nothing to analyse, and that is the job of a free trading journal that fills itself from your broker instead of being typed in by hand.
P&L isn't enough
Every trader's first reflex is to look at their P&L, and that's normal, but it's insufficient. P/L, P&L and PnL are three spellings of the same number, and none of them says why. The P&L is an overall result that hides everything that matters: it doesn't tell you whether you win from your edge or by luck, whether your performance is steady or carried by a few shots, or where your leaks are. Settling for the P&L is like judging an engine by the sound it makes alone.
Analyzing means opening the hood. It's breaking down this overall result into its causes, to understand not just how much you win or lose, but why. This shift from result to causes is the heart of performance analysis, and it's what makes improvement possible. You can only act on what you understand, and the P&L alone can't be understood. Two traders can post the same balance at month's end while running radically different trading, one solid and reproducible, the other fragile and lucky, and only analysis tells you which side you're actually on.
The indicators that count
A good analysis rests on a few well-chosen indicators, not an avalanche of numbers. The most useful count on one hand, and their definitions barely change from one tool to the next. The MetaTrader 5 help page on the testing report gives these: the profit factor is the ratio of gross profit to gross loss, the expected payoff (the expectancy) is the average return of one trade, and the maximal drawdown is the gap between a balance high and the low that follows it. Add the win rate, your share of winning trades, and the average R: in the Van Tharp Institute's trading concepts, R is the initial risk of a trade, and expectancy is the mean of the results expressed as multiples of that risk. Together, they paint a complete portrait of your trading.
| Indicator | What it tells you |
|---|---|
| Win rate | How often you win |
| Profit factor | Whether your system is profitable and how much |
| Expectancy | What each trade returns on average |
| Max drawdown | Your worst drop, your risk resistance |
| Average R | Your performance in units of risk |
These indicators are read together, never in isolation. A good win rate means nothing if the profit factor is bad; a high profit factor on a small sample isn't reliable; a huge drawdown can threaten an otherwise profitable system. It's the combination of these numbers that gives the true portrait, and learning to read them together is the first skill of performance analysis. Each formula, and how to read them side by side, is covered in our guide to trading statistics.
Breakdowns reveal the why
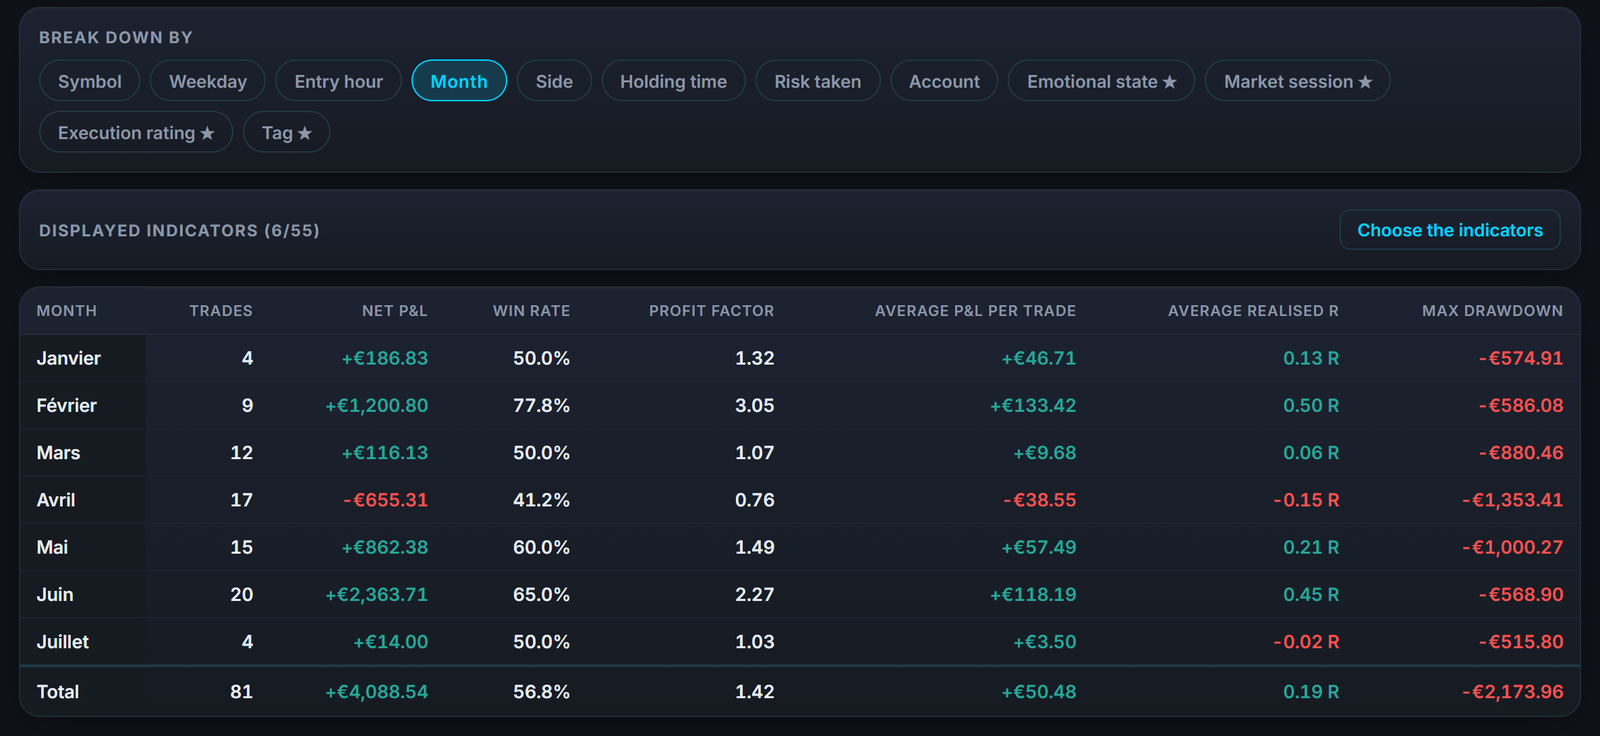
Global indicators tell you the general health of your trading, but not where your results come from. For that, you must break down: look at your statistics by time of day, by day, by instrument, by setup and by emotional state. These breakdowns surface the concrete sources of your gains and losses, invisible in the global numbers.
It's in the breakdowns that the most actionable lessons hide. Discovering that an instrument systematically loses for you, that a time window concentrates your best trades, or that a degraded emotional state coincides with your worst days gives you precise action levers. Analysis by global indicators tells you whether you're doing well or badly; analysis by breakdowns tells you why and where to act.
Trading frequency is one of those breakdowns, and research has measured it on stocks. Across 66,465 households with accounts at a large US discount broker from 1991 to 1996, Barber and Odean's study Trading Is Hazardous to Your Wealth finds very little difference in gross performance between those who trade the most and those who trade the least, but a net annual return of 11.4% for the former against 18.5% for the latter: the gap comes from transaction costs. Those figures describe individual investors in US stocks over that period, not day trading, forex or futures. They are a reminder of two things only: a result is read net of costs, and your number of trades deserves its own line in the analysis.
Consistency and distribution
Beyond averages, a good analysis looks at the consistency and distribution of your results. Two traders with the same P&L can have opposite profiles: one wins small amounts steadily, the other depends on rare big gains among many losses. Neither profile is bad in itself, a method that cuts losses fast and lets winners run looks like the second, but they are not steered the same way, and this difference only appears if you look beyond the average. The Van Tharp Institute in fact describes any trading system as a distribution of R-multiples, of which expectancy is only the mean.
Analyzing the distribution of your trades and days tells you where your performance really comes from. A simple test: remove your best trade and recompute. If all your gain comes from one or two exceptional trades, your result rests on very few observations, and you need more trades before believing it. A classic measure of that consistency is the Sharpe ratio, which, according to William Sharpe's 1994 article in the Journal of Portfolio Management, relates the average differential return against a benchmark to the variability of that differential: for the same average gain, the steadier result earns the better ratio. Understanding this dimension changes how you manage your risk and judge the solidity of your edge.
From analysis to action
An analysis that leads to nothing is useless. The goal isn't to contemplate numbers, but to draw concrete decisions from them. Each analysis should conclude with one or two clear actions: repeat a winning pattern more, cut a losing one, adjust a failing component. It's this move to action that turns analysis into progress. It is also the test for choosing what stays on your trading dashboard.
The finest analysis is worth nothing if it doesn't change a single one of your behaviors. The goal isn't to understand for the sake of understanding, but to understand in order to act.
To be effective, this action must stay targeted: better a single well-applied change than ten vague resolutions. Analysis gives you the map, but it's action, one at a time, verified at the next analysis, that moves you forward. It's this loop, analyze, act, re-measure, that constitutes the real engine of progress, far more than the passive accumulation of statistics.
Analyze regularly, not once
Performance analysis only has value if it's regular. A one-off analysis gives a snapshot at a given moment, but it's tracking over time that reveals trends: is your edge strengthening or degrading, are your corrections bearing fruit, is a new problem appearing? Without regularity, you don't see these evolutions, and you always react too late.
Integrating analysis into a routine, a weekly review for example, turns a one-off exercise into a continuous steering tool. You see your numbers evolve, compare periods, measure the effect of your adjustments. This regularity is what separates the trader who steers their progress from the one who suffers their results. Analysis isn't an exceptional audit, it's a background habit.
A worked example to understand expectancy
Take an illustrative example to understand why expectancy matters more than win rate alone. Imagine a trader with a 40% win rate: they lose six trades out of ten. If they risk 1R per trade, average 3R on winners and lose 1R on losers, their expectancy is: (0.4 x 3R) minus (0.6 x 1R), which is 1.2R minus 0.6R, an expectancy of +0.6R per trade. Over ten trades, that is 12R won for 6R lost, so a profit factor of 2, and a breakeven point at 25% winning trades. This trader loses more often than they win, and yet their system stays profitable as long as those averages hold. Run your own counts and your own averages through the win percentage calculator and you get the same three figures on real trades: the rate, the threshold it has to clear, and the expectancy that follows.
Conversely, imagine a second trader with a flattering 70% win rate, but who averages 0.5R on winners and loses 1.5R on losers. Their expectancy becomes: (0.7 x 0.5R) minus (0.3 x 1.5R), which is 0.35R minus 0.45R, a negative expectancy of -0.1R per trade. Over ten trades, 3.5R won for 4.5R lost: a profit factor of 0.78, when with those averages they would need 75% winning trades just to break even. This second trader feels like a winner far more often, yet loses money over time. This example illustrates why focusing on win rate alone, without crossing it with the average-gain-to-average-loss ratio, leads to misleading conclusions about a strategy's real quality.
Compare your periods rather than compare yourself to others
Useful analysis happens over time, not just at a single moment. Compare your current month to your previous month, your quarter to the one before, rather than measuring yourself against an outside number or a performance other traders display. Your own trajectory is what tells you whether you're progressing, stagnating or regressing, and it's the only comparison that's truly actionable, because you control the levers of your own evolution, not someone else's.
This across-time comparison reveals things a single snapshot never shows: a profit factor slowly improving despite a choppy P&L, a maximum drawdown shrinking trade after trade, or conversely a gradual degradation that would go unnoticed if you only looked at the account balance. Setting up this periodic tracking, even a simple one, turns analysis from a one-off exercise into a real steering tool for your progress.
Interpretation traps to avoid
Analyzing your performance carries its own traps. The first is over-interpreting a small sample. The Van Tharp Institute asks for at least thirty trades to get a first idea of your expectancy, and rather one to two hundred for a clear picture. The confidence interval calculation presented in the NIST statistics handbook, from the US standards institute, shows why: a 60% win rate measured over 20 trades sits, at 95% confidence, between roughly 39% and 78%, a range too wide to conclude anything; over 100 trades, between 50% and 69%. And every breakdown shrinks the sample: 200 trades spread over five setups is 40 trades per setup on average. The second trap is confusing correlation with causation in your breakdowns: because a setup performed better in a given month doesn't mean it's structurally superior, it may simply reflect that period's market conditions.
The third, subtler trap is confirmation bias, which Raymond Nickerson's 1998 review in the Review of General Psychology defines as seeking or interpreting evidence in ways that are partial to what you already believe. Applied to your numbers, it means retaining what confirms your opinion of your strategy and downplaying what contradicts it. A trader convinced their favorite setup is excellent risks skimming over statistics showing the opposite. The counter is to set, before looking at your numbers, the precise questions you want answered, rather than searching afterward for a story that reassures you.
Analyzing execution, not just the result
One dimension of performance analysis the P&L doesn't show is the gap between your plan and your actual execution. Two trades can have exactly the same result in R and yet reveal opposite realities: one was taken exactly to your rule, the other was taken outside the setup but won by luck. If you only analyze results, these two trades look alike; if you analyze execution, they tell completely different stories. One of these execution gaps is documented: across 10,000 accounts at a US discount broker from 1987 to 1993, Terrance Odean's study of the disposition effect shows stock investors realizing their gains more readily than their losses.
That's why a complete analysis always crosses financial performance with plan fidelity: what proportion of your trades actually respected your entry criteria, your planned stop placement, your exit rule. A trader can have a positive P&L for a month while having very low plan fidelity, which suggests their success owes more to luck than to their system. And a good result does not repeat by itself: in the study by Barber, Lee, Liu and Odean of stock day traders in Taiwan, from 1992 to 2006, about 13% of the roughly 360,000 day traders of an average year end up profitable after fees, but fewer than 1% go on to predictably outperform the following year. Those figures hold for that market and that period, not for forex or futures. Spotting this gap early, before it turns into a loss, is one of the most valuable contributions of rigorous analysis.
Documenting qualitative context, not just numbers
Numeric indicators tell part of the story, but not the whole story. Two trades identical on paper (same setup, same result in R) can have been experienced very differently: one taken calmly according to plan, the other taken under tension after a short night's sleep or a personal argument. These qualitative elements show up in no classic numeric indicator, yet they can explain why a trader executes well one day and poorly the next, with a strictly identical strategy.
Noting this qualitative context next to each trade, even briefly, enriches your analysis when you revisit it later. You can then cross your under-performance moments not only with objective variables (time, instrument, setup) but also with your general life state at the time of the trade. This extra layer of analysis, more qualitative than quantitative, usefully complements numeric indicators without ever replacing them, and can surface patterns invisible in the statistics alone.
How Tradoshi analyzes your performance
Tradoshi automatically computes all your indicators and breakdowns on your real trades, without any spreadsheet. You get a complete, up-to-date analysis on every sync, ready to lead to action.
- Key indicators (win rate, profit factor, expectancy, drawdown, average R) computed automatically.
- Breakdowns by hour, day, instrument and setup to understand where your results come from.
- Oshi Score that summarizes your performance across several axes into an overall rating.
- Tracking over time to see whether your edge strengthens and your corrections work.
Frequently asked questions
How do I analyze my trading performance?
By going beyond the P&L to understand where your results come from. Look at a few key indicators (win rate, profit factor, expectancy, drawdown, average R) read together, then break down your performance by time, instrument, setup and emotion to reveal the why. Always conclude with one or two concrete actions.
Why isn't P&L enough?
Because the P&L is an overall result that hides everything that matters: it doesn't tell you whether you win from your edge or by luck, whether your performance is steady or carried by a few shots, or where your leaks are. Analyzing means opening the hood and breaking down this result into its causes, to understand not just how much but why.
Which indicators should I watch to analyze my trading?
A handful suffice: the win rate (win frequency), the profit factor (profitability), the expectancy (average gain per trade), the maximum drawdown (worst drop) and the average R (performance in units of risk). They're read together, never in isolation: it's their combination that gives the true portrait of your trading.
Why look at consistency and not just the average?
Because two traders with the same P&L can have opposite profiles: one wins small amounts steadily, the other depends on rare big gains among many losses. Analyzing the distribution of your results tells you where your performance really comes from, and how many trades it truly rests on.
How often should I analyze my performance?
Regularly, ideally in a routine like a weekly review. A one-off analysis gives a snapshot, but tracking over time reveals trends: is your edge strengthening, are your corrections working, is a problem appearing? Regularity separates the trader who steers their progress from the one who suffers their results.
Why doesn't a high win rate guarantee profitability?
Because profitability depends on expectancy, which crosses win rate with the average-gain-to-average-loss ratio. A trader with a 70% win rate but small average gains and bigger average losses can have negative expectancy, while a trader who loses 60% of the time but with a favorable gain/loss ratio can be solidly profitable.
How do I avoid confirmation bias when analyzing my trades?
By setting, before looking at your numbers, the precise questions you want answered, rather than searching afterward for a story that confirms what you already believe about your strategy. A trader convinced their favorite setup is excellent will otherwise tend to skim over statistics showing the opposite.