 By Benjamin Roure L'Hermitte
RSI trading starts with knowing what the Relative Strength Index is: a momentum oscillator bound between 0 and 100 that compares the average gain to the average loss of the last 14 candles. Read well, it's a useful context tool. Misread, it's the fastest way to short a stock that keeps climbing for three more days while you sit there in a losing position. Let's break down what it really measures, what published research says about it, and more importantly, what it doesn't tell you.
- The RSI measures the speed and size of recent price moves, not where price is headed next.
- The 70 and 30 zones are not automatic buy or sell triggers, they just flag an acceleration in momentum.
- Divergences are the best-known reading of this indicator, and the documentation describing Wilder's method warns that they mislead in a strong trend.
- Published studies test precise rules on stock indices, mostly before costs: none gives a general success rate for the RSI.
- No indicator replaces a plan and risk management, understanding the RSI alone doesn't give you an edge.
What the RSI actually is
The RSI, or Relative Strength Index, is a momentum indicator created by J. Welles Wilder, who introduced it in 1978 in his book New Concepts in Technical Trading Systems. That is what StockCharts' ChartSchool page on the RSI and TradingView's help page on the RSI write, the two pieces of documentation this article follows, the book itself not having been consulted. The core idea is simple. It measures whether recent gains have been stronger than recent losses, over a set lookback period. The result shows up as a line oscillating between 0 and 100, sitting below your price chart.
When the RSI climbs, it means green candles have been dominating lately, both in number and in size. When it drops, red candles took over. Nothing mystical about it. It's a momentum calculation, not a crystal ball. Treating it like a binary switch, above 70 sell, below 30 buy, is the misreading this article wants to spare you, and we'll get into why.
The RSI formula (without drowning you in math)
You don't need to calculate the RSI by hand, your charting software does it for you. But understanding the logic behind it changes how you read it.
The calculation happens in two steps. First the Relative Strength (RS): the average gain over the period divided by the average loss over that same period, 14 candles by default, the length Wilder recommended according to MetaTrader 5's help page on the RSI. Then that value gets converted into the 0-100 scale: RSI = 100 − 100 ÷ (1 + RS). One detail StockCharts spells out: the very first average is a simple average of the first 14 changes, and every average after that is smoothed Wilder's way, previous average times 13, plus today's change, all divided by 14. Today's RSI therefore depends a little on the whole history loaded, which explains small differences between two programs that don't have the same number of candles behind them.
In practice: if over the last 14 candles gains averaged twice the size of losses, RS equals 2 and the RSI reads 66.7. If losses are four times the size of gains, RS equals 0.25 and the RSI reads 20. On a series recomputed by hand for this article, fifteen closes rising from 100 to 110 with four one-point pullbacks give an average gain of 1 and an average loss of 0.29: RS 3.5, RSI 77.8. A single following candle down two points, smoothed Wilder's way, brings the RSI back to 69.5. That's the whole mystery solved: a relative strength comparison, nothing more, nothing less.
Overbought, oversold: what these zones really tell you
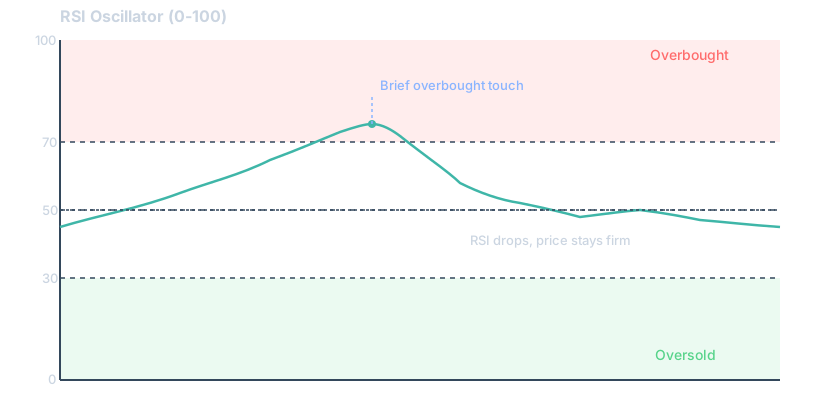
Here's trap number one. An RSI above 70 means gains have dominated the last candles, not that the market is about to fall. StockCharts says it plainly: a momentum oscillator can become overbought, or oversold, and stay that way in a strong trend. You short it thinking you're being clever, and you get run over by a trend that just keeps going.
Same thing works in reverse. An RSI under 30 in a real downtrend can stay glued to the floor for a long stretch. Wong, Manzur and Chew's study of the Singapore stock market, published in Applied Financial Economics in 2003, puts it in one sentence: used in a trending market, the RSI often becomes entrenched near one end of its range for days, or even weeks, giving false indications of a top or a bottom. The market has zero obligation to bounce just because an indicator prints a low number.
What these zones actually flag is excess speed. The move has been fast and one-directional. That can precede a pause, a consolidation, or yes, sometimes a reversal. But it can also just precede... more of the same move. The RSI gives you context, not an execution order. The authors of the Singapore study offer that very reading to explain their mixed results on the 70 and 30 rules: the RSI is useful in a non-trending market, and indiscriminate use of it leads to dismal results. That's exactly where reading market structure becomes non-negotiable, and why a solid setup pairs the RSI with other tools, like moving averages to place your entries and exits within the broader trend.
RSI divergences: the best-known reading, and the most misunderstood
If you keep only one thing from this whole article, make it this: the divergence. That's when price and the indicator start telling two different stories.
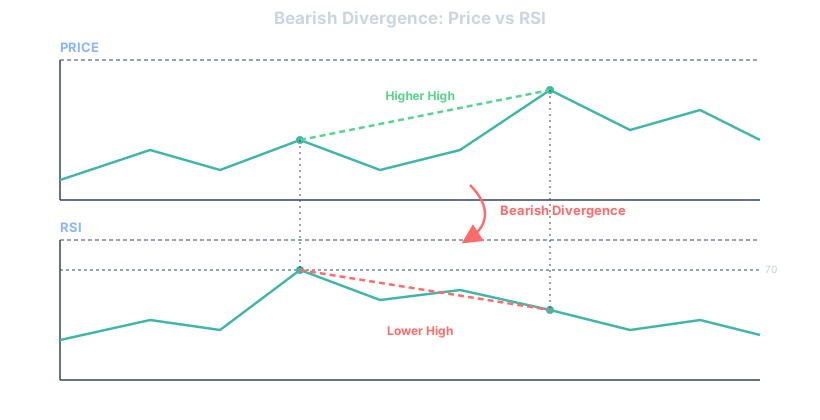
A bearish divergence, as StockCharts defines it, happens when price makes a higher high than the previous one, but the RSI makes a lower high. Translation: price is still climbing, but the force behind the move is fading. Fewer buyers, less conviction. It doesn't mean a crash is coming right now, but it's a warning sign worth watching.
Bullish divergence works the opposite way: price makes a lower low, but the RSI makes a higher low. Sellers are losing steam even though price keeps drifting down. What the documentation says about it is more cautious than the legend: StockCharts warns that divergences are misleading in a strong trend, that a strong uptrend can show numerous bearish divergences before a top materializes, and TradingView's help page reports Andrew Cardwell's reading, for whom a divergence usually causes a brief price correction, not an actual trend reversal.
Careful though. Divergences alone aren't entry signals. They tell you a move is running out of gas, not exactly when the tank goes empty. The classic trap is jumping in on the first divergence, when the move can line up several of them before it actually turns. That's where a trading plan with precise entry rules makes the difference between profiting from a divergence and getting trapped by one.
What published research says about the RSI
The RSI has been tested in peer-reviewed journals, and what those studies measure is narrower than what it gets credited with. Wong, Manzur and Chew applied the RSI to the daily closes of Singapore's Straits Times Industrial Index, from January 1, 1974 to December 31, 1994. Only the 50 crossover rule, buy when a 6-period RSI rises back above 50 and sell when it falls back below, yields significantly positive returns over the whole period; the methods built on the 70 and 30 zones, touch, peak and retracement, give mixed results the authors don't even publish. And costs are not counted: the retail commission in Singapore was a flat 1 % at the time, and the authors write that their results apply mostly to member firms of the exchange, which paid none.
Chong and Ng, in Applied Economics Letters in 2008, tested the RSI and the MACD on monthly data of the London Stock Exchange's FT30 index, from July 1935 to January 1994, and conclude that both rules generate returns higher than buy-and-hold in most cases. With Liew, they ran the test again on the daily closes of five other indices, Milan, Toronto, DAX, Dow Jones and Nikkei, from January 1976 to December 2002: according to their abstract, the RSI(21, 50) rule stands out on the Milan Comit and Toronto's S&P/TSX, and the RSI(14, 30/70) rule, buy when the RSI rises back above 30 and sell when it falls back below 70, on the Dow Jones.
Taken one by one, each of these results is good news for the RSI. Taken together, they are a reminder that a test depends on the exact rule, the period, the market and the costs. Park and Irwin, in the Journal of Economic Surveys in 2007, reviewed 95 modern studies of technical trading rules, all families included: 56 find positive results, 20 negative results and 19 mixed results, and the profits concentrate before the early 1990s. They add that most of these studies suffer from problems in their testing procedures, data snooping, ex post selection of trading rules, poorly estimated risk and transaction costs.
That data snooping has been measured. Sullivan, Timmermann and White, in Data-Snooping, Technical Trading Rule Performance, and the Bootstrap, published in the Journal of Finance in 1999, tested 7,846 parameterizations of technical rules on a hundred years of daily Dow Jones prices, from 1897 to 1996: the best rule beats the benchmark from 1897 to 1986, even after adjusting for the bias, but not over the next ten years, from 1987 to 1996, nor on S&P 500 index futures since their launch in 1984. None of those rules is an RSI, they come from five families, filters, moving averages, support and resistance, channel breakouts and volume, but the lesson holds for any setting: a parameter kept because it worked on the past is judged on data it has not seen.
What you can take from this fits in three points. These tests cover stock indices, on daily or monthly data, not forex or crypto on a five-minute chart. The results depend on the precise rule, 50 crossover or 70 and 30 zones, on the period and on the market, and they are mostly given before costs. And none of these studies gives a success rate for the RSI: that's why you won't find one in this article, and why the only statistic that matters is the one from your own trades.
The classic mistakes traders make with the RSI
I've seen, and made, every single one of these. Here they are, no filter.
- Treating every touch of 70 or 30 as an automatic signal, without checking the surrounding trend context first.
- Forgetting the RSI can stay extreme for a long time in a strong trend, and eating several counter-trend stops in a row.
- Hunting for divergences everywhere, even where none really exist, because you desperately want a signal that confirms what you already believe.
- Using the RSI in isolation, with no support or resistance, no market structure, no other filter at all.
- Tweaking the RSI period over and over until you find a setting that would have worked on the last five trades, which tells you nothing about the future.
That third point deserves a second look. Desperately wanting to see a divergence because you're already in a position and looking for a reason to stay in it, that's exactly the mechanism behind the confirmation bias that keeps you holding a losing trade. The RSI only becomes dangerous when you bend it toward what you want to see instead of what it's actually showing you. The fifth point has a name in the research, data snooping, and it's the bias Sullivan, Timmermann and White quantified on a hundred years of the Dow Jones: a setting found after the fact is worth nothing until it has been judged on data it hasn't seen.
Combining the RSI with other tools, the smart way
The RSI on its own is still an incomplete tool. It knows nothing about price levels, nothing about volume, nothing about structure. It just compares the speed of gains to the speed of losses over a rolling window.
The simplest combination is a trend read upstream, through moving averages or a structure of higher highs and lows, sometimes with key price zones added on top. A bearish RSI divergence that shows up right at a major resistance zone doesn't read like an isolated one floating in the middle of nowhere, and it's your journal's job to say whether it's really worth more.
Another combination, which StockCharts reports after Constance Brown: in a bull market, the RSI tends to fluctuate between 40 and 90, with the 40-50 zone acting as support; in a bear market, between 10 and 60, with the 50-60 zone acting as resistance. Hence the RSI as a timing filter on a trend-following strategy: you wait for a clear uptrend, then use an RSI pullback toward 40-50, not 30, as your entry zone, instead of waiting for an extreme oversold reading that might never show up in a strong trend anyway.
Some indicators build that combination into the oscillator itself. The Traders Dynamic Index starts from a 13-period RSI, adds a signal line and wraps volatility bands around it: the crossover gives the timing, the bands show whether momentum is leaving its usual range.
Before stacking oscillators, know that they all ask the same question. The stochastic locates the close within the recent range, momentum and the ROC compare the close to the one n candles ago, the MACD crosses two exponential moving averages. Seeing them agree with the RSI is not a double confirmation, it's a single piece of information, speed, read several times. Volatility is another question, the one the ATR answers, and trend strength a third one, which the DMI and ADX answer.
Setting the RSI period for your trading style
The default period is 14: it's the one Wilder recommended, MetaTrader 5's help page recalls, adding that 9-period and 25-period settings have also become popular. That's a decent starting point, not a rule carved in stone. Shorten the period and the RSI gets twitchier, more reactive, with more false signals. Stretch it out and it smooths and slows down, at the risk of reacting too late, and the Singapore study makes the same remark: the longer the period, the less frequent and more stable the signals, the shorter the period, the noisier they get.
The table below is common practice, not a measurement: none of the documentation or studies read for this article ties a period to a trading style.
| Trading style | Common RSI period | Behavior |
|---|---|---|
| Scalping | 5 to 9 | Very reactive, lots of signals, lots of noise too |
| Day trading | 9 to 14 | Good balance between reactivity and reliability |
| Swing trading | 14 to 21 | Smoother, filters out micro-moves better |
| Position trading | 21 and up | Rare signals, but usually more meaningful |
There's no universal magic setting. What matters is testing your configuration on enough history before you trade it live, instead of guessing. That's exactly the kind of question you settle by backtesting a strategy without lying to yourself about the results you got.
How Tradoshi helps you
The RSI can help you read a market's context. But the question that actually matters, in the end, is this: are YOUR trades based on the RSI actually profitable, over time, with your risk management? Not the indicator in theory. Your trades, in reality.
That's exactly what Tradoshi lets you check. By logging every trade with the setup you used, you can isolate every trade taken on an RSI divergence, or on a 40-50 pullback, and look at their real numbers: win rate, risk-reward ratio, expectancy. Not your gut feeling after three wins in a row, but figures across a large enough sample.
Tradoshi's discipline score also plays a quiet but useful role here. It flags whether you're actually following your RSI entry rules or improvising the moment the market speeds up. And the risk management module makes sure a good-looking RSI signal never turns into an oversized position just because you got a little too confident. The indicator gives you the idea. The journal gives you the proof.
Before you take your next RSI trade
The RSI is a strong context tool. A weak prediction tool. The difference between the two comes down to how you use it: as one filter among several, or as a magic button that says buy here, sell there. Traders who actually get better with this indicator are the ones who accept its limits and check, with real numbers, what genuinely works for them, rather than trusting a textbook rule blindly. If you're serious about that verification step, it starts with keeping a trading journal that's actually useful rather than a spreadsheet you abandon after a week.
Frequently asked questions
What's a good RSI value to buy or sell?
There isn't one universal number. Below 30 suggests a stretched downside move, above 70 an extended upside move, but both can persist much longer than expected in a strong trend. Treat these levels as context, not triggers.
Why does the RSI stay above 70 for so long sometimes?
Because strong trends keep producing bigger gains than losses for extended periods. The RSI reflects that dominance, it doesn't cap it. Staying overbought is often a sign of strength, not weakness.
Is a bullish divergence a buy signal by itself?
No. It's a warning that selling pressure is fading, which often precedes a bounce, but timing still needs confirmation from price action or structure before you enter.
What RSI period should beginners use?
Start with the default 14. It's a reasonable balance between reactivity and reliability, and it lets you learn how the indicator behaves before you start tweaking settings you don't fully understand yet.
Can the RSI be used alone as a full strategy?
Technically yes, practically it's risky. Without market structure, trend context, or risk management around it, RSI signals alone tend to generate too many false entries in trending markets.
Does the RSI work the same way on crypto as on stocks?
The math is identical: it only needs closing prices. What published research has measured is narrower, stock indices on daily or monthly data, and none of the studies cited here covers crypto. Whether your zones or your period need adjusting is a question for your journal, not for a rule of thumb.
What's the difference between RSI and momentum indicators like MACD?
Both measure momentum, but the RSI is bounded between 0 and 100 and focuses on the ratio of gains to losses, while the MACD tracks the relationship between two exponential moving averages and has no fixed range.
How do I know if a divergence is reliable or just noise?
No study cited here measures it. StockCharts' documentation warns that divergences are misleading in a strong trend, and that a strong uptrend can show several bearish divergences before a top forms. Look for them after an extended trend, near a key support or resistance zone, and log them so your own numbers can answer.
Has the RSI been tested in published research?
Yes, on precise rules and stock indices. Wong, Manzur and Chew find a 50 crossover profitable on Singapore's index from 1974 to 1994, before costs; Chong and Ng find the RSI and the MACD beating buy-and-hold on London's FT30 on monthly data from 1935 to 1994; Park and Irwin note that most such tests suffer from data snooping and poorly estimated costs. None gives a general success rate for the RSI.
Should I change my RSI settings for every asset I trade?
Not randomly. It's fine to adjust the period based on your holding time frame, but changing settings asset by asset just to fit recent price action is a form of overfitting that rarely holds up going forward.
Can the RSI help with position sizing?
Not directly. The RSI tells you about momentum, not about how much capital to risk. Position sizing should come from your risk management rules, independent of what any single indicator is showing.