 By Benjamin Roure L'Hermitte
Trading rules are decisions made cold, before the session, that fix what you will do in a specific situation: how much you risk, when you stop, what you leave alone. Having them is useless if you don't hold them, and holding them is far harder than writing them. The real challenge of discipline isn't knowing what to do, it's doing it when everything in you pushes to do otherwise. Here's how to define rules that work, what research has measured about commitments made in advance (and on whom), and above all how to make your rules solid enough to withstand emotion.
- A good rule is precise and verifiable, not a vague good intention.
- Few well-held rules beat many ignored ones.
- Rules matter most in the hot moments, when emotion wants you to deviate.
- A rule you don't measure is a rule you probably don't respect.
- What's been measured comes from elsewhere: savings, deadlines, habits; no published study measures the effect of written rules on retail traders' results.
Everyone knows you need rules in trading. The problem was never knowing it, it's holding. A trader can recite their ten rules by heart and break them all in the same session, swept up by a loss, an urge to win back, or a move they don't want to miss. Discipline isn't played out in knowing the rules, it's played out in respecting them under pressure.
The good news is that holding your rules isn't a matter of heroic willpower, it's a matter of design. Well-built rules almost hold themselves; badly-built ones break at the first stress. This guide explains what makes a good rule, why you need few, and how to make them inviolable by measuring them. A written rule is only worth something if you know how often you kept it: that is what a discipline score counts, trade by trade, instead of leaving it to memory.
What makes a good rule
A good trading rule has three qualities: it's precise, it's verifiable, and it's decided cold. Precise, because a vague rule leaves room for interpretation, and interpretation under emotion always leans the wrong way. Verifiable, because a rule you can't check afterward constrains you to nothing. Decided cold, because a rule invented in the heat of action is already a capitulation.
| Bad rule (vague) | Good rule (precise, verifiable) |
|---|---|
| I manage my risk well | I risk 1% max per trade |
| I don't overtrade | I take 3 trades max per day |
| I stop if things go badly | I stop after 3 losses in a row |
| I trade at the right times | I only trade 8-11am and 2:30-5pm |
| I stay disciplined | I never move a stop against myself |
Notice the difference: each good rule on the right can be verified on your real trades by a simple yes or no. That's a rule that constrains. The phrasings on the left sound good but oblige you to nothing, because they can never be objectively declared violated.
Few rules, well held
The classic mistake of the conscientious trader is to pile up rules. Twenty ultra-detailed rules give an impression of total control, but they're impossible to hold all at once, and you end up respecting none. Discipline doesn't come from the number of rules, it comes from their constant respect.
Better five rules you hold 100% than twenty you hold halfway. Pick the few rules that address your real leaks (the ones costing you the most money), and focus all your energy on those. Once they've become automatic, you can add others. Discipline is built brick by brick, not by pouring a whole wall at once.
What research has measured about rules set in advance, and on whom
A trading rule has the form 'if this situation, then this action': if I have three losses in a row, then I stop. That format has been studied outside the markets under the name of implementation intentions. The meta-analysis by Gollwitzer and Sheeran, published in 2006, pools 94 independent tests: deciding in advance how to respond to a situation had a medium-to-large effect (d = 0.65) on goal attainment, across varied goals, among participants in psychology studies, not traders. It doesn't say a written rule makes you money; it says a decision made before the situation holds better than a general intention.
Commitment made in advance has also been measured on money, the money of savings. In the Save More Tomorrow program by Thaler and Benartzi, published in the Journal of Political Economy in 2004, employees committed in advance to directing part of their future pay raises to retirement savings. At the first company, a midsize American manufacturer, 78% of the employees offered the plan joined, 80% of those enrolled were still in it after the fourth raise, and participants' average saving rate went from 3.5% to 13.6% over 40 months. Those are employees and savings, not traders and a stop; but the mechanism is that of a rule: the decision is made while it still costs nothing, and then applies without being reopened.
Deadlines tell the same story. In the study by Ariely and Wertenbroch, published in Psychological Science in 2002, 99 professionals taking an executive-education course at MIT had three papers to hand in: the section given three evenly spaced deadlines by the instructor averaged 88.76, against 85.67 for the section free to set its own dates. In a proofreading task paid per error found, 60 students then caught the most errors with evenly spaced imposed deadlines, fewer with deadlines they chose themselves, and the fewest with a single final deadline. Participants willingly imposed costly constraints on themselves, and it helped; a constraint set from outside, which can't be renegotiated, helped more. Those are students and assignments, not traders; this article keeps only this: a rule checked by something other than your mood of the moment holds better than a resolution.
In finance, the closest thing concerns orders set in advance. The laboratory experiment by Fischbacher, Hoffmann and Schudy, a 2014 University of Konstanz working paper, gave one group of participants stop-loss and take-gain orders that sold automatically: according to its abstract, the only part read here, that group showed a significantly smaller disposition effect, and the reduction came from an increase in realized losses. The bias itself, selling winners too early and keeping losers too long, was measured by Odean on 10,000 accounts at a large US discount brokerage between 1987 and 1993, retail stock investors: 14.8% of paper gains were realized against 9.8% of paper losses, and the winners sold then beat the losers kept by 3.4 points over the following year. These investors weren't day trading.
And among retail traders? As far as we know, no published study measures the effect of written rules on their results. No figure in this section transfers to your account: a saving rate that triples or a grade of 88 against 85 says nothing about a drawdown. What these studies have in common, and it's all this article borrows from them, is that a decision made before the situation, and checked by something other than the mood of the moment, holds better than an intention. The rest is measured on you, rule by rule, in your journal.
Why rules cave under pressure
A rule is never tested when all is well. It's tested precisely in the moments when you most want to break it: after a stinging loss, facing an explosive move, when you're behind on your monthly target. That's where you manufacture tailor-made exceptions for yourself: 'this time is different', 'I really feel it', 'just once'. These exceptions are the exact mechanism by which rules die.
A rule that allows a 'just this once' exception is no longer a rule, it's a suggestion. And suggestions protect no one.
The counter isn't to trust yourself more in those moments, it's to make the exception costly and visible. You often read that willpower is a reservoir that drains over the day; the coordinated replication by Hagger and colleagues, run in 2016 in 23 laboratories on 2,141 participants, measured an effect close to zero (d = 0.04, with a confidence interval that includes zero). So the argument isn't that your willpower runs out: it's that an intention gets renegotiated, whereas a breach logged and displayed in black and white doesn't. The little voice pleading for an exception runs into a measurable reality.
Making your rules inviolable: measurement
This article's bet is that the difference between a trader who holds their rules and one who breaks them isn't strength of character, it's feedback. The bet has support outside trading: the meta-analysis by Harkin and colleagues, published in 2016 in Psychological Bulletin, pools 138 studies and 19,951 participants randomly allocated to a prompt to monitor their progress or to a control condition; monitoring progress promoted goal attainment (d = 0.40), and more so when the information was physically recorded or made public. That result is about goals in general, not trades. When you don't measure your rule adherence, you live in the comfortable fog where you can tell yourself you're 'broadly disciplined'. That fog is the breeding ground of indiscipline. It lets you minimize each breach and never see the overall pattern.
When, conversely, each rule is automatically checked on your trades and turned into a score, the fog vanishes. You see exactly which rule you break most, under what conditions, and what it costs you. What was an impression becomes data, and data you can correct. It's the most direct lever you have for turning written rules into real discipline, and the only one that gets verified on your own trades.
How to define your first rules
If you're starting from scratch, don't try to cover everything. Look at your worst past trades and ask: what simple rule would have prevented each of them? Those are your priority rules, the ones closing your real leaks. Here's a common starting point, to be checked against your own leaks:
- Maximum risk per trade (say 1% of capital).
- Maximum number of trades per day, to avoid overtrading.
- A stop rule after a defined number of consecutive losses.
- Allowed time windows, to trade only when your edge exists.
- An absolute ban on moving a stop against yourself.
Entry rules, management rules, exit rules
Not all rules are alike, and it's useful to classify them by moment of the trade. Entry rules define what you take: which setups, in what conditions, at what times. Management rules define what you do once in position: your risk, where you place your stop, whether you move it or not. Exit rules define how you close: target, trailing stop, partial exit. It's tempting to polish your entry rules and neglect the other two categories.
It's a mistake, because the best-documented bias among retail investors lives at the exit: the disposition effect Odean measured on the accounts described above, where paper gains were realized more readily than paper losses. A good trade badly managed or badly closed becomes a bad result. By covering all three moments with clear rules, you eliminate improvisation where it costs most. Check that your rule set doesn't focus solely on 'when to enter': the rules telling you what to do once the trade is already running are at least as important.
The 'one at a time' rule
Correcting several bad habits at once means watching several fronts at the same time, and it's precisely under pressure that the watching lapses. That's why the best way to anchor new rules is to work on them one at a time. Pick the rule that addresses your costliest leak, focus only on it until it becomes an automatism, then move to the next. Count in months rather than days: Lally and colleagues followed 96 volunteers, mostly postgraduate students, who repeated a simple eating, drinking or exercise action every day for 12 weeks; among the 39 whose curve fitted the model well, automaticity plateaued after 66 days on median, from 18 to 254 days depending on the person, and that was an isolated action, not a trading rule. To know where it stands, track that trading habit day after day rather than trusting your impression. This sequential approach seems slow, but it asks less of you than trying to hold everything at once.
This method has another advantage: each mastered rule strengthens your confidence in your ability to hold the next. You build a streak of accumulating wins, instead of a long list of failures confirming that you 'lack discipline'. What repetition produces is automaticity: an action repeated in the same context ends up demanding less attention, and that's exactly what you want from a rule on the day you're tired or tempted to force. By working one rule at a time, you turn a crushing goal ('become disciplined') into a sequence of reachable steps.
Writing your rules down
A rule that exists only in your head isn't really a rule: it's vague, revisable at will, and emotion rewrites it without you noticing. Writing your rules down freezes them, gives them an objective existence you can't quietly bypass. The mere fact of having to formulate them in writing, which is the heart of a trading plan, forces you to make them precise, and reveals those that were too vague to be applied.
Keep your written rules visible while you trade, as a pilot keeps their checklist. It's not a lack of confidence in your memory: in the United States, federal rule 14 CFR 121.315 requires airlines to provide a cockpit check procedure designed so that a crew member will not need to rely on memory for the items to be checked, and which the flight crew must follow when operating the aircraft. The regulator doesn't say pilots have poor memories; it decides that a safety procedure isn't built on memory. Written, displayed rules confront you in real time with what you'd decided cold, and that confrontation is exactly what holds you back from deviating. What's written resists; what stays in the head bends.
Evolving your rules without betraying yourself
A rule isn't set in stone forever: it can and should evolve as your strategy matures, your capital grows, or you discover new leaks in your trading. The trap isn't changing a rule, it's changing it at the wrong moment and for the wrong reason. Evolving a rule after a cold analysis of several weeks of trades is legitimate; loosening it mid-trade because it's in your way never is.
Good practice is to reserve rule revision for a dedicated moment, like your weekly or monthly review, never during a trading session. Ask yourself coldly: has this rule cost me more than it protected over the period, backed by data rather than a momentary impression? If the answer is yes repeatedly and measurably, adjust it. If the answer comes from a single bad day where the rule stopped you from taking a trade that would have won, leave it alone: the randomness of one case never overturns a rule built on dozens of observations.
The context rules you forget
Beyond the obvious risk and entry rules, some less-cited rules deserve their place. A rule on the number of screens or tabs open at once, to avoid the cognitive overload that pushes you to jump from one opportunity to another. A rule on the minimum state required to trade (sleep, calm, absence of major upset), because a good setup taken tired or angry is no longer quite the same trade. A rule on maximum size after an exceptional gain, so euphoria doesn't inflate your risk right after a great streak.
These so-called context rules easily fall through the cracks because they don't concern the trade itself, but the conditions under which it's taken. Yet an error isn't always a bad setup: sometimes it's a good setup taken in bad conditions, tired, distracted, rushed. Nobody has measured the share of each among retail traders; your journal can measure it for you. Widening your rules to cover this context, not just the trading action itself, closes leaks that classic rules don't see.
Personal rules vs imposed rules: the difference
If you trade for a prop firm, you deal with two layers of rules: the ones the firm imposes on you (daily loss limit, maximum drawdown, sometimes forbidden hours) and the ones you set for yourself. According to FTMO's trading objectives page, read in October 2026, its maximum daily loss is 5% of the initial capital on the 2-Step model and 3% on the 1-Step model, its maximum loss 10%, all measured on equity, open positions included; these figures change, reread your firm's page. A tempting mistake is treating the firm's rules as the only ones that matter, and trading right up to their exact limits, with no personal margin. That's risky, because an imposed rule that closes your account the moment it's hit leaves you no room for execution error or an exceptionally bad day.
Imposed rules don't only come from prop firms either. In the United States, FINRA Rule 2270 requires a broker that promotes day trading to hand each retail customer, before the account is opened, a written disclosure whose first point says that day trading can be extremely risky. The text is fixed in advance by the regulator and delivered before the first trade, not during it: a rule, whoever writes it, is read cold.
Good practice is to set personal rules noticeably more conservative than the imposed ones, creating a safety margin between your own limit and the one that, if crossed, ends the evaluation or the funded account. A trader who stops at -3% personal daily loss, while the firm's limit is -5%, protects themselves against an accidental overshoot caused by slippage or an execution mistake. This margin isn't excessive caution, it's risk management applied to the rule itself.
This layered approach also helps when you manage several funded accounts or several evaluations at once, each with its own limits. Rather than tracking each firm's rules separately in your head under pressure, decide a single personal standard stricter than the strictest of them, and apply that one standard everywhere. It's far easier to hold one consistent rule across every account than to remember which exact percentage applies to which firm in the middle of a losing trade.
How Tradoshi makes you hold your rules
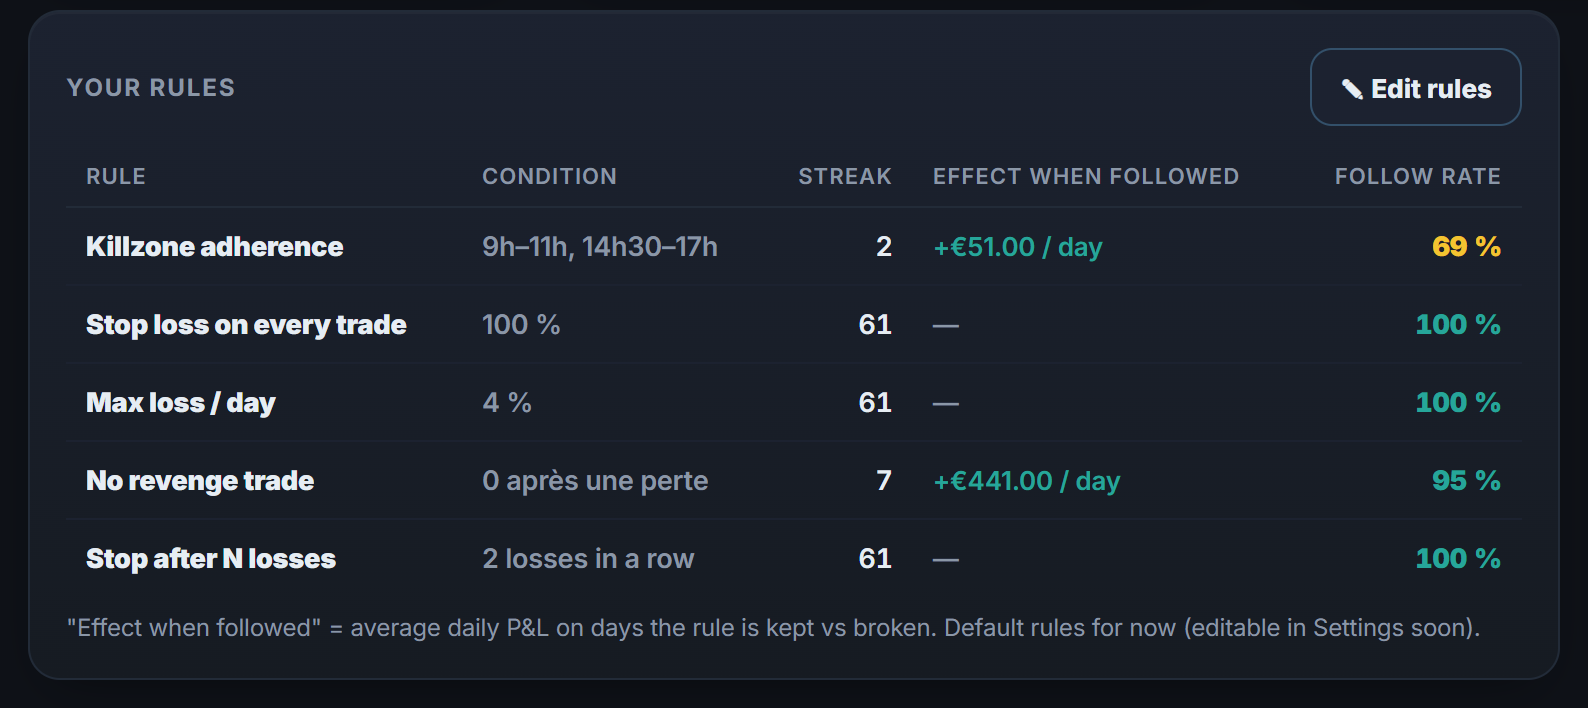
Tradoshi takes your rules and automatically checks them on each of your real trades, then condenses it all into a daily discipline score. Your rules stop being a list you forget and become a mirror that reflects, every day, the truth about your plan adherence.
- Rules verified: risk, killzones, stop after N losses, daily limit checked on your real trades.
- Discipline score: a daily 0-100 grade quantifying your overall rule adherence.
- Weak point identified: the rule you break most is highlighted so you can work on it.
- History: your streaks of disciplined days become visible and reinforce themselves.
Frequently asked questions
How do I define good trading rules?
A good rule is precise, verifiable and decided cold. Precise to leave no room for interpretation, verifiable to check it on your trades by a simple yes or no, decided cold so it isn't a capitulation invented in action. 'I risk 1% max per trade' is a rule; 'I manage my risk well' isn't.
How many rules should I have?
Few, but well held. Twenty detailed rules give an illusion of control but are impossible to respect all at once. Better five rules held 100% than twenty held halfway. Pick the ones closing your real leaks (what costs you most), make them automatic, then add others brick by brick.
Why can't I hold my rules?
Because rules are never tested when all is well, but in the moments you most want to break them: after a loss, facing a big move, behind on your target. You then manufacture 'just this once' exceptions for yourself. The counter isn't more willpower but making each breach visible and measured.
How do I make my rules more solid?
By measuring them. Without feedback, you live in a comfortable fog where you think yourself 'broadly disciplined' and minimize each breach. When each rule is checked on your trades and turned into a score, the fog vanishes: you see which rule you break most and what it costs. Measurement turns written rules into real discipline.
Which rules should I start with?
Look at your worst past trades and ask what simple rule would have prevented each. A good start: max risk per trade (1%), max trades per day, stop after N consecutive losses, allowed time windows, and a ban on moving a stop against yourself. These five rules are a starting point, not a universal list: your journal will tell you which ones concern you.
Should rules be rigid or flexible?
Rigid on the survival principles (risk, stop, exit), flexible nowhere on those points. A rule that allows a 'just this once' exception is no longer a rule, it's a suggestion, and suggestions protect no one. You can evolve your rules cold, between sessions, but never loosen them in the heat of action.
Can I change a rule if it no longer suits me?
Yes, but only during a dedicated review, done cold, never during a trading session. Analyze several weeks of data before concluding a rule costs you more than it protects. A single bad day where the rule stopped you from taking a winning trade is never enough to overturn it: the randomness of one isolated case carries no weight against dozens of observations.
Which context rules are easy to forget?
Context rules: the minimum state required to trade (sleep, calm), a size limit after an exceptional gain to stop euphoria from inflating risk, or the number of tabs open at once to avoid cognitive overload. An error isn't always a bad setup: sometimes it's a good setup taken in bad conditions, and only your journal can say in what proportion for you.
Should my personal rules match my prop firm's rules exactly?
No, they should be stricter. Trading right up to the firm's exact limits leaves you no room for an execution slip or an exceptionally bad day, since crossing them can end the account instantly. Setting a personal threshold noticeably more conservative than the imposed one, for example stopping at -3% when the firm's limit is -5%, creates a real safety margin.
Does any study prove that written rules improve a trader's results?
Not as far as we know. What's been measured comes from elsewhere: 'if-then' implementation intentions (Gollwitzer and Sheeran, 94 tests, d = 0.65), advance commitment on employees' savings (Thaler and Benartzi, saving rate from 3.5% to 13.6% over 40 months), deadlines imposed on students (Ariely and Wertenbroch) and, in the laboratory, sell orders set in advance that reduce the disposition effect (Fischbacher, Hoffmann and Schudy). None of these studies concerns retail traders.