 By Benjamin Roure L'Hermitte
What is leverage in trading? It is the ability to control a position bigger than the money you put down: at 30:1 leverage, 1,000 of margin carries a 30,000 position. Beginners see it as a gain accelerator, when it is an amplifier of consequences, in both directions. Used well, it's a plain technical setting. Used badly, it turns a small mistake into a loss that takes the account. The truth is that leverage is almost never your real problem: your position size is.
- Leverage doesn't increase your edge, it amplifies what you're already doing, for better or worse.
- What matters isn't the leverage offered, but the real risk of your position.
- A high available leverage obliges you to nothing: you can use a tiny fraction of it.
- The real danger is sizing your position from the leverage instead of from your risk.
A broker advertising 1:500 leverage isn't doing you a favor: it lets you open a position five hundred times bigger than your margin, and so lose that margin on a 0.2% move. Leverage lets you control a position far bigger than your capital. On the gross result it is neutral: it multiplies your gains and your losses alike. On the net result it isn't quite, because costs are charged on the full position. The trouble mostly comes from what traders do with it.
The good news is that once you understand the link between leverage, position size and risk, leverage stops being a danger and goes back to being what it is: a simple setting. This guide explains what leverage really is, why it's only an amplifier, and how to neutralize it by always thinking in risk rather than in multiplier.
What leverage really is
Leverage is the ability to control a position whose value exceeds your capital. A 1:100 leverage means that with 1,000 you can open a 100,000 position. The broker, in a sense, lends you the difference, and only asks you to deposit a margin to cover potential losses. It looks like magic, but there's no magic: you carry all the risk of the full position, not just of your margin.
That's where the confusion is born. The beginner looks at their leverage and thinks 'I can make a hundred times more'. They forget the second half of the sentence: '...and lose a hundred times more'. Leverage creates no value, it merely enlarges the scale. On a position with no statistical edge, big leverage just accelerates ruin.
Leverage and margin are two ways of writing the same number: required margin equals 1 divided by leverage. 1:100 leverage means a margin of 1% of the position, 30:1 leverage means 3.33%, 2:1 leverage means 50%. Read the other way, the adverse move that wipes out the whole margin of a position opened at the limit is also 1 divided by leverage: 1% at 1:100, 3.33% at 30:1, 50% at 2:1, before costs.
Leverage limits by country and product
Maximum leverage isn't yours to pick freely: for a retail client, the regulator caps it, product by product. In the European Union, ESMA's statement of 27 March 2018 announced leverage limits on the opening of a position for CFDs sold to retail clients, from 30:1 to 2:1 depending on the volatility of the underlying, and ESMA's statement on the adoption of those measures sets their application from 1 August 2018. Those European measures were temporary. In France, the AMF's release on its national intervention measures states that it takes them over from 1 August 2019, with the same scope. In the United Kingdom, the FCA's policy statement PS19/18 imposes the same range, 30:1 to 2:1, from 1 August 2019.
| CFD underlying (retail client, EU) | Maximum leverage | Initial margin | Adverse move that triggers the 50% close-out |
|---|---|---|---|
| Major currency pairs | 30:1 | 3.33% | 1.67% |
| Non-major currency pairs, gold, major indices | 20:1 | 5% | 2.5% |
| Other commodities and non-major equity indices | 10:1 | 10% | 5% |
| Individual equities | 5:1 | 20% | 10% |
| Cryptocurrencies | 2:1 | 50% | 25% |
The last column is a calculation, not a regulator's figure: it assumes an account holding only the margin of a single position opened at the limit, and ignores the spread and costs. It applies the close-out rule described further down, which requires the provider to close out when the funds in the account fall to 50% of the required margin. The margin percentages are those in the annex of the AMF's decision of 1 August 2019 on CFDs (in French), which counts as major pairs those made of two currencies among the US dollar, the euro, the yen, the pound sterling, the Canadian dollar and the Swiss franc.
In the United States, the rules cover other products. On retail forex, the CFTC's release on its retail forex rules, effective October 18, 2010, leaves it to the National Futures Association to set the security deposit within limits provided by the Commission. Section 12 of the NFA's Financial Requirements sets it at 2% of the notional value for ten listed currencies, including the euro, the yen, the British pound and the Swiss franc, which is 50:1 leverage, and at 5% for the others, which is 20:1. On stocks bought on margin, the SEC's investor bulletin on margin accounts notes that the Federal Reserve Board's Regulation T lets you borrow up to 50% of the purchase price, which is 2:1 leverage at the open, and that FINRA rules then require you to keep equity of at least 25% of the value of the securities.
These limits apply to retail clients of brokers supervised by these regulators. A 1:500 leverage offered to a retail trader today therefore falls under a different framework, whether a different client status or a broker established elsewhere. Before the European measures, the AMF's decision notes that leverage applied to CFDs across the Union ranged from 3:1 to 500:1.
Leverage is only an amplifier
Here's the fundamental point: leverage adds nothing to your edge. If your strategy has positive expectancy, it stays positive with or without leverage; if it has negative expectancy, leverage just accelerates the losses. Leverage is a multiplier, and multiplying a bad result by a hundred gives a very bad result, faster.
Leverage doesn't make a bad trader good. It makes a bad trader broke faster, and a good but reckless trader just as vulnerable.
That idea is liberating, because it shifts your attention from leverage (whose ceiling isn't up to you: the regulator caps it, your broker sets it) to the only thing that counts: the real risk you take on each position. Once you think in risk, the leverage figure becomes almost anecdotal.
The real number to watch: your true risk
Available leverage tells you nothing about what you really risk. What counts is the percentage of your capital you lose if your stop is hit, and that depends on your position size and stop distance, not on the maximum allowed leverage. You can have a 1:500 account and risk only 0.5% per trade, or a 1:10 account and ruin yourself risking 30%. Leverage is just a ceiling, not an obligation.
| Situation | Leverage offered | Trade's real risk | Verdict |
|---|---|---|---|
| Prudent | 1:500 | 0.5% | Healthy |
| Reasonable | 1:100 | 1% | Healthy |
| Reckless | 1:30 | 10% | Dangerous |
| Suicidal | 1:100 | 40% | Ruin imminent |
The table shows the same leverage can cover completely opposite behaviors. High leverage with a small real risk is perfectly healthy; modest leverage with a huge risk is deadly. Stop judging a trade on its leverage, judge it on its real risk as a percentage of your capital.
The mistake that burns accounts
The fatal mistake is sizing your position from the available leverage rather than from your risk. The beginner thinks: 'I have 1,000 and 1:100 leverage, so I can open 100,000, let's go'. They open the maximum position their margin allows, and a 1% move against them is worth 1,000, their entire capital. They won't even get to that 1%: the broker closes the position earlier, once the margin is no longer covered. They let leverage decide their size, when their risk should have decided it.
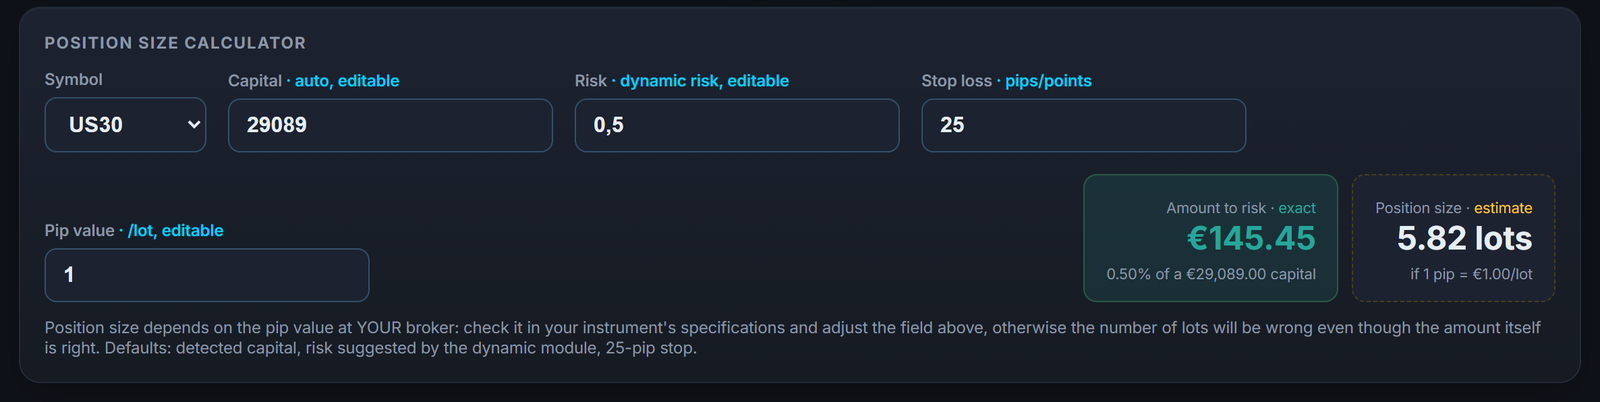
The healthy approach is exactly the reverse: you start from your accepted risk (1% of capital), look at the distance to your stop, and derive the position size. Leverage never enters this calculation, it merely makes the position technically possible. If your computed size exceeds what your leverage allows, that's the only time leverage becomes a real constraint again.
Leverage is only one piece of the framework: risk percentage, stop, daily limit and maximum drawdown are summed up in the guide to risk management in trading.
The margin-call trap
A word on the margin call, the penalty for over-leverage. Strictly speaking, it is your broker's demand that you deposit more funds when your losses eat into the required margin. But nothing obliges the broker to wait for your answer: the SEC's definition of a margin call states that the firm can sell your securities to cover the shortfall without informing you in advance, and that it decides which ones. On CFDs sold to retail clients in the European Union, closing is even an obligation: the provider must close out one or more positions when the funds in the account fall to 50% of the minimum required margin. You then take your loss with no choice, at a price you didn't decide. Trading with a modest risk keeps you far from that threshold; trading at maximum leverage brings you closer with every adverse tick.
The automatic close-out doesn't guarantee that the loss stops at your margin. If price jumps from one level to another, the position is closed further away than planned and the account can go below zero: the AMF's decision of 1 August 2019 on CFDs (in French) reports that after such gaps, clients owed far more than they had invested. That is the reason for the negative balance protection imposed on retail CFDs, which limits the loss to the funds in the account. It only holds within that framework: on a stock margin account, the SEC bulletin cited above warns that you can lose more money than you have invested. The first safeguard is still a stop placed before entry, whose limits are detailed in the guide to take profit and stop loss.
Why brokers offer so much leverage
It's worth understanding why spectacular leverage (1:500, 1:1000) gets put forward. It isn't generosity: costs follow the size of the position, not your deposit. The AMF's decision on CFDs puts it this way: transaction fees are normally applied to the full notional value of the trade, so investors incur higher fees as their funds are committed at higher leverage. The same text adds that high leverage makes the position more sensitive to small price moves, and so more exposed to automatic close-out, and that existing studies associate lower leverage with better outcomes for clients. High leverage promises big gains on small capital; what it raises for certain is the costs and the speed at which a mistake gets paid for.
Regulators have also measured how these accounts end up. According to ESMA's statement of 27 March 2018, analyses by national authorities across several EU countries show that 74 to 89% of retail accounts lose money on CFDs, with average losses per client ranging from €1,600 to €29,000. In France, the AMF study published in 2014 (in French) counts more than 89% of losing clients among 14,799 clients active on CFDs and forex, over four years taken between 2009 and 2013 depending on the broker. Those figures are about leveraged products sold to retail clients, not about all traders. The AMF states that it could not study the link between the leverage used and the result; what it observes is that the loss grows with the average order size and with the number of orders.
That clarity changes your relationship with the leverage offered: it isn't a gift to exploit to the maximum, it's a tool of which you use the fraction that suits you. A savvy trader sees 1:500 leverage as mere technical flexibility (they'll be able to take the position they need), not as an invitation to load up. The difference between the trader who survives and the one who burns out often comes down to this single interpretation: the first sees a ceiling, the second sees a target.
Effective leverage: the real indicator
Beyond the maximum leverage your broker allows, there's a far more useful number: your effective leverage, i.e. the ratio between the total value of your open positions and your capital. If you have 10,000 in capital and 30,000 in open positions, your effective leverage is 3:1, whatever the maximum leverage your broker allows. It's that number, not the ceiling, that reflects the real risk you carry at a given moment.
Monitoring your effective leverage spares you the insidious trap of accumulation. You can take several modest positions that, together, represent a huge exposure without you realizing, because each seems reasonable on its own. Effective leverage aggregates everything and tells you the truth about your overall exposure. A low effective leverage is a far better health indicator than your account's maximum leverage, which says nothing about what you actually do.
Leverage and instrument volatility
The same leverage doesn't carry the same danger depending on the instrument you trade. A 1:20 leverage on a calm currency pair has nothing to do with 1:20 on a very volatile index or a crypto that moves 10% in a day. What matters is the asset's possible move multiplied by your leverage: it's that product that determines the scale of your capital swings, not the leverage figure in isolation. At an effective leverage of 20, a 0.5% move shifts your capital by 10%, and a 10% move by 200%, twice what you have in the account.
That's why you should adapt your effective leverage to the volatility of what you trade: less leverage on jumpy assets, a bit more on calm ones, always within your risk-per-trade limit. A trader who applies the same leverage to all instruments takes, unknowingly, very different risks from one market to another. Reasoning in real risk (how much I lose if my stop is hit) rather than in leverage automatically solves this, because it already incorporates volatility via the stop distance. It also means your leverage settings should evolve as an instrument's volatility changes over time, rather than staying fixed forever: a currency pair that was calm for months can suddenly become erratic around a major economic release, and a leverage level that was reasonable last week can become reckless overnight without you touching a single setting.
Classic mistakes beyond over-sizing
Over-sizing isn't the only way to misuse leverage. Another mistake is averaging down on a losing position by using available leverage to open extra size, hoping to lower your average entry price. That practice, already risky without leverage, becomes explosive with it: each addition increases your total exposure and brings you closer to a margin call at the exact moment the market is proving you wrong.
Another classic mistake is changing size mid-streak, reacting to your results rather than to your plan. After several wins, the temptation to increase effective leverage to 'speed things up' is strong; after several losses, the temptation to increase it to 'win it back' is just as strong. Either way, you let your emotional state drive your exposure, which is the exact opposite of consistent risk management.
Finally, leverage weighs on your tolerance for volatility. A position with high effective leverage makes your balance swing far more violently on screen, which can wear down your composure and push you to exit a good trade too early or panic on a normal move. Leverage doesn't just affect your account, it directly affects your ability to execute your plan calmly.
A worked example: two traders, same capital
Imagine two traders starting with 5,000 each on the same instrument. The first uses 2:1 effective leverage and risks 1% of capital per trade, so 50. With a 45% win rate and a 1.8 reward-to-risk ratio, their expectancy is 0.45 × 1.8 − 0.55 = +0.26 times the risk per trade. Over a hundred trades, they end the year with a steady climb in capital, modest balance swings, and the mental capacity to keep executing their plan without being rattled by fluctuations.
The second trader, with the same strategy, the same stop and the same win rate, uses 16:1 effective leverage and therefore risks 8% of capital per trade. On paper, their expectancy per trade is eight times larger. But a streak of five consecutive losses costs them 1 − 0.92 to the power of 5, about 34% of their capital, where it costs the first trader 4.9%. That streak is nothing unusual: with 55% losing trades drawn independently, the probability of meeting at least one over a hundred trades is about 92%. After a 34% drop, you need to gain back nearly 52% to return to the starting point. Facing that drop, the danger is to abandon the plan, cut size in a panic, then ramp it back up after a win to compensate, and finish the year worse off than if they had kept their original risk. What the size of the risk does to the probability of losing everything is the subject of the guide to risk of ruin.
This example illustrates a simple truth: the same statistical edge produces radically different psychological and financial trajectories depending on the real risk level applied, regardless of whether the underlying strategy is a winner on paper.
Leverage and swing trading: the cost of carry
Leverage has a cost the day trader doesn't pay as long as they close within the day: financing or swap fees on positions held overnight. The AMF's decision on CFDs notes that financing charges, daily or overnight, are usually applied to keep a CFD open; on a stock margin account, it is the interest on the loan. The bigger your position thanks to leverage, the heavier this carrying cost, which follows the size of the position rather than your margin, weighs if you hold for several days or weeks. A swing trader using the same effective leverage as a day trader can see a significant chunk of their gain eaten away by these accumulated fees. In forex, that swap is logged trade by trade: the forex trading journal guide shows where to read it and how to track it.
That doesn't mean avoiding leverage in swing trading, but that your risk calculation should treat this carrying cost as a variable in its own right, not a footnote. A trader comparing two similar setups should also compare their respective carrying costs if positions are held for several days, because that cost can turn a paper-winning trade into one that's barely profitable once fees are deducted. Reducing effective leverage on positions held longer is a simple way to limit that effect.
Keeping it under control with Tradoshi
Leverage only becomes a problem when you lose sight of your real risk. Tradoshi computes, on each trade, the percentage of capital you actually engaged, so you always think in risk and never in multiplier.
- Real risk per trade: the percentage of capital engaged is computed from your stop, regardless of leverage.
- Over-sizing detection: trades where your size blows past your usual risk stand out.
- Management consistency: your average risk tells you whether you use leverage with discipline or in fits.
- Crossed with drawdown: you see the direct impact of over-leveraged trades on your capital curve.
Frequently asked questions
What is leverage in trading?
It's the ability to control a position whose value exceeds your capital. A 1:100 leverage lets you open a 100,000 position with 1,000 in margin. You carry the risk of the full position, not just your margin: leverage amplifies your gains and losses alike, it creates no value by itself.
What leverage should I use without burning out?
The question is misframed: don't think in leverage but in real risk. Whatever leverage your broker offers, size your position to risk only a small fraction of your capital per trade, for example 0.5 to 1%. With that discipline, you can have a 1:500 account and stay perfectly prudent, because you only use a fraction of it.
What is the maximum leverage allowed for a retail trader?
It depends on the country and the product. On CFDs sold to retail clients in the European Union, the limits announced by ESMA in 2018 range from 30:1 on major currency pairs to 2:1 on cryptocurrencies, and they were taken over in 2019 by the AMF in France and by the FCA in the United Kingdom. In the United States, retail forex is limited to 50:1 on the main currencies and 20:1 on the others, and buying stocks on margin to 2:1 at the open.
Is high leverage dangerous?
Available leverage is only a ceiling, not an obligation. High leverage with a small real risk is perfectly healthy; modest leverage with a huge risk is deadly. The danger is never the leverage figure, it's sizing your position from it rather than from your accepted risk.
Does leverage increase my chances of winning?
No. Leverage adds nothing to your edge: it multiplies what you're already doing, for better or worse. If your strategy has positive expectancy, it stays positive with or without leverage; if it's a loser, leverage just accelerates the losses. Multiplying a bad result by a hundred gives a very bad result, faster.
How do I size my position with leverage?
Always start from your risk, never from leverage. Decide how much you're willing to lose (1% of capital), look at the distance to your stop, and derive your size. Leverage doesn't enter this calculation: it merely makes the position technically possible. It only becomes a constraint again if your computed size exceeds what it allows.
What is a margin call?
It's your broker's demand that you deposit more funds when your losses eat into the required margin. The broker doesn't have to wait: it can close your positions without warning, and on CFDs sold to retail clients in the European Union it must do so when the funds in the account fall to 50% of the minimum required margin. You then take your loss with no choice. Trading with a modest risk keeps you far from that threshold; trading at maximum leverage brings you closer with every adverse tick.
What other leverage mistakes exist besides over-sizing?
Averaging down with leverage (adding to a losing position to lower your entry price, which increases exposure at the worst moment), changing your size in reaction to your results rather than your plan, and underestimating leverage's effect on your composure: a position with high effective leverage swings your balance more violently, which wears down your discipline even if the percentage risk is theoretically acceptable.
Does leverage cost anything if I hold positions for several days?
Yes, financing or swap fees on positions held overnight follow the size of the position, not your margin. The higher your effective leverage, the heavier that carrying cost weighs if you hold for several days or weeks. In swing trading, that cost deserves a place in your risk calculation, since it can significantly eat into a trade that's a winner on paper.