 By Benjamin Roure L'Hermitte
Money management trading decides what your strategy becomes. It turns a statistical edge into real gains, or ruins a good system whose positions are too big. At the heart of it all, one question keeps coming back: should you risk a fixed amount or vary your risk? This guide answers it, with the calculations and their sources.
- Money management doesn't create an edge, it decides what yours becomes: oversized positions ruin a winning system.
- Fixed percentage risk: the essential base, it protects in bad patches and compounds in good ones.
- Dynamic risk: a refinement for advanced traders, useful but dangerous if it serves to load up under emotion.
- The percentage is a setting, not a law: 0.5 to 1% is a starting convention, to check against your own trades.
You can have a winning strategy and still ruin yourself: risking too much on each trade is enough. Money management doesn't replace strategy, though. Edward Thorp puts the two problems in order: find a bet with a positive expectation, then decide how much of your capital to put on it (Thorp, The Kelly Criterion in Blackjack Sports Betting, and the Stock Market). This guide deals with the second: how much to risk, and how to adjust your size.
The classic debate pits two schools against each other: fixed risk (you always risk the same percentage of your capital) and dynamic risk (you modulate that percentage by context). You'll see what position size changes in the result of one and the same system, how each approach works, which to choose for your level, and the mistakes that cost the most.
Why money management decides what your strategy becomes
A strategy gives you a statistical edge: over many trades, it wins a little more than it loses. That edge only materializes over a large number of trades, and money management decides whether you'll still be there to take them.
The Van Tharp Institute illustrates it with its simulated games, in which every participant starts with $100,000 and gets the same trades: after 50 trades, it reports final equities ranging from bankrupt to $13 million, position sizing and individual psychology being the only two factors involved (Van Tharp Institute's trading concepts). Same trades, opposite results.
The math says the same. As early as 1956, J. L. Kelly showed that a gambler with an edge who bets his entire capital each time ends up broke with probability one if he plays indefinitely, and that one precise fraction of capital maximizes its growth (Kelly, A New Interpretation of Information Rate). Thorp works out a case: with 53% winning bets paid at even money, growth is fastest when betting 6% of capital, and above about 12% the capital heads toward zero despite the edge.
What each percentage does to the probability of losing everything, with the formula and a simulation, is detailed in the guide to risk of ruin.
Fixed percentage risk: the base
The basic approach is fixed percentage risk of capital: you risk a constant percentage on every trade, and your position size follows from your stop distance. In the Van Tharp Institute's example, 1% of a $100,000 portfolio is $1,000 of risk; for a stock bought at $23 with a stop at $17.25, that is $5.75 of risk per share, so the position is 173 shares ($1,000 ÷ $5.75, rounded down).
Everything starts from the stop, then: where to put it so that it marks the scenario's invalidation rather than an amount you accept to lose is explained in the guide on where to place a stop loss.
This method has two properties you can compute. It slows the fall in drawdowns: since the percentage applies to your current capital, your size shrinks with each loss. Ten losses in a row at 1% cost 9.6% of the account, not 10%, and a fixed fraction below 100% cannot, in theory, take capital to zero, Thorp notes. And it compounds in good phases: when your capital rises, your 1% represents more money, without your relative risk having increased.
| Property | Effect |
|---|---|
| Size adapted to the stop | Constant risk whatever the setup's volatility |
| Percentage of current capital | Automatically brakes in drawdown |
| Compound growth | Gains grow with capital |
| Simplicity | One rule to hold, hard to bypass |
Dynamic risk: promise and danger
Dynamic risk means varying your risk percentage by context. There are healthy versions and deadly versions, and the whole point is not to confuse them. Healthy versions rely on objective criteria: reducing your risk in drawdown to protect yourself, adjusting it to market volatility, or raising it very gradually as capital grows. Deadly versions rely on emotion: loading up because you 'feel it', increasing to win back after a loss.
The distinction is simple but crucial. Dynamic risk decided cold, by written rules, can improve already-solid management. Decided in the heat of action, by mood, it is over-risk disguised as method. The pull has been measured: among Chicago Board of Trade proprietary traders, Coval and Shumway observe above-average afternoon risk, taken to recover from morning losses. That is revenge trading with a nice name.
Increasing your risk because you're confident isn't a strategy, it's an emotion. The market doesn't know your confidence level.
Fixed or dynamic: which to choose?
Until you have a long, profitable track record, the answer is fixed risk, and on the low side. The right fraction depends on an edge you only know approximately, and Thorp writes that betting too much is much more severely penalized than betting too little: by his calculations, at half the Kelly fraction you keep three quarters of the growth, and the chance of ever losing half your capital drops from one in two to one in eight. Dynamic risk only makes sense once that base is proven by data.
| Your profile | Starting setting, to test |
|---|---|
| Beginner or unproven system | Fixed risk at 0.5% |
| Regular trader, measured edge | Fixed risk at 1% |
| Advanced trader, proven discipline | Fixed at 1%, defensive dynamic possible |
| Trader who wants to 'win it back' | Fixed risk, no exceptions |
These percentages are starting conventions, not proven thresholds: 1% is simply the figure the Van Tharp Institute uses in its example. The same page asks for one defensive adjustment: that your rule reduce position size while the account is dropping. When you hesitate, go back to fixed.
The pillars of sound management
Beyond the fixed/dynamic debate, all solid risk management rests on a few non-negotiable principles that reinforce each other:
- Always a stop loss: it makes your loss planned and decided cold, the starting point of the risk calculation.
- A computed position size, never chosen on feel, from your risk and your stop distance.
- A daily loss limit that stops you before emotion takes control.
- Attention to correlation: several positions on the same idea are one big risk in disguise.
- A measure after the fact: check that your real risk matches your rules, not just your intentions.
Each of these pillars deserves a guide of its own, and you'll find them in this collection. But they share one philosophy: deciding cold what your emotional self will only have to execute. Risk management, at its core, is protecting yourself from yourself.
The mistake that ruins even good traders
There is one mistake a good system doesn't forgive: varying your risk under the sting of emotion. After a loss, increasing size to win back. After a gain, loading up because you feel invincible. In a drawdown, doubling to 'catch up'. That last reflex can be computed: starting at 1% of capital and doubling after each loss, six losses in a row cost 63% of the account (1 + 2 + 4 + 8 + 16 + 32), and the next bet, 64%, is more than what is left.
The protection against this mistake doesn't rest on willpower alone, but on a written rule and on measurement. When your real risk is tracked trade after trade, the days you slipped show up in black and white, and you can correct before they become a habit. What stays vague doesn't get corrected.
Risk management at the portfolio level
Money management doesn't stop at risk per trade, it also covers the risk of all your positions together. You can perfectly respect your 1% on each trade and still be over-exposed, if several positions bet on the same idea or if you accumulate too many open trades at once. The real question isn't only 'how much am I risking on this trade?' but 'how much am I risking in total, right now, if the worst scenario plays out?'.
A mature management therefore incorporates a global risk limit: a cap on the number of simultaneous positions, on the cumulative risk engaged, and on exposure to one market idea. Without this portfolio safeguard, a trader disciplined trade by trade can still end up with dangerous exposure at the account scale, simply through accumulation. Thinking in aggregate risk, and not just line-by-line risk, is the shift from being a trader to being a manager of your own capital.
Adapting your management to your horizon
Good risk management also depends on your trading horizon. A scalper taking dozens of trades a day doesn't have the same approach as a swing trader holding positions for several days. The first must closely watch fee accumulation and overtrading risk; the second must manage the risk of holding positions through announcements and opening gaps. The fixed-risk principle applies to both, but its concrete implementation varies.
Likewise, your management must adapt to the nature of your capital. Trading your savings, a prop firm account or a small account you can afford to lose don't call for the same prudence. On a prop firm account the limit is written down: in FTMO's two-step challenge, for example, the maximum daily loss is 5% of initial capital and the maximum loss is 10% (FTMO's trading objectives). At 1% of initial capital per trade, five losses in the same day use up the whole day's allowance.
Risk management as a competitive edge
Risk management is often presented as a defensive constraint. That's an incomplete view. A market edge can wear out once it is known: across 97 variables shown to predict stock returns, McLean and Pontiff measure portfolio returns 58% lower after the study describing them was published. A position sizing rule depends on no market anomaly: nobody can wear it out for you.
It isn't enough to win: with no edge, there is nothing to protect. But it decides how long you last. A modest risk lets you get through the bad patches and stay in the game long enough for an edge, however thin, to produce its effects, where an oversized position cancels it.
A worked example: fixed risk through a losing streak
Take a trader with 15,000 in capital, risking a fixed 1% per trade (150 on the first trade). They hit seven losses in a row. With a 50% win rate and independent trades, a streak that long shows up in about one series of 200 trades out of two. Because each loss is computed on the current, shrinking capital, the amounts risked shrink with each loss: 150, then 148.50, then about 147, and so on, ending the streak down 6.8%, not 7% flat. The account is bruised, not broken, and the trader can keep executing their plan exactly as before.
Now imagine the same trader risking a flat 5,000 per trade, an amount chosen when the account was larger and never adjusted downward. Three losses are enough: 3 × 5,000 is the whole 15,000, and the account is empty four trades before the streak ends. A flat amount stays the same while the account shrinks; a fixed percentage shrinks with it. That difference matters most during the streaks that decide whether you're still trading next month.
Common sizing mistakes that undermine good money management
Understanding fixed percentage risk in theory doesn't stop small, seemingly harmless habits from undermining it. None of these mistakes look dramatic in isolation, a slightly rounded-up lot size here, a stop moved 'just a little' there. But rounding 0.37 lot up to 0.4 already raises the risk of that trade by about 8%, and repeated over dozens of trades, these habits push your real risk above the 1% you set, without you ever deciding to take on more risk. The gap between intended risk and real risk is the number to measure.
- Recomputing risk on starting capital instead of current capital, so the percentage silently drifts from the intended risk as the account moves.
- Rounding position size upward 'just this once' on a setup that feels particularly strong.
- Treating a stop loss as a suggestion rather than a hard exit, which turns a known, bounded risk into an unbounded one.
- Forgetting to recompute size after adding to a position, so a scaled-in trade ends up risking far more than planned.
The fix isn't more willpower, it's structure: a fixed formula applied the same way every time, and a system that checks your real risk against your rule after the fact. Left unchecked, these small drifts are invisible trade by trade and only become obvious once you look at the pattern across a month or a quarter.
When to revisit your risk percentage
A fixed risk percentage isn't meant to be fixed forever, only fixed within a given period. There are legitimate moments to revisit it, always downward in doubt, and only upward with hard evidence. A meaningful drawdown is one trigger: you can write an explicit rule that cuts your risk percentage in half after losing a set portion of capital, and restores it only once you've rebuilt a track record of disciplined execution. A change in market conditions, unusually high volatility, unusually thin liquidity, is another legitimate trigger to size down temporarily.
On the upward side, the bar should be much higher: months of consistent execution, a measured edge with enough trades behind it to be statistically meaningful, and a track record showing your real risk has matched your intended risk trade after trade. Raising your percentage without that evidence is exactly the emotional dynamic risk this guide warns against, dressed up as a rational decision. Revisiting your risk percentage should be a rare, deliberate, data-driven event, not a running negotiation with yourself.
How Tradoshi helps you on risk
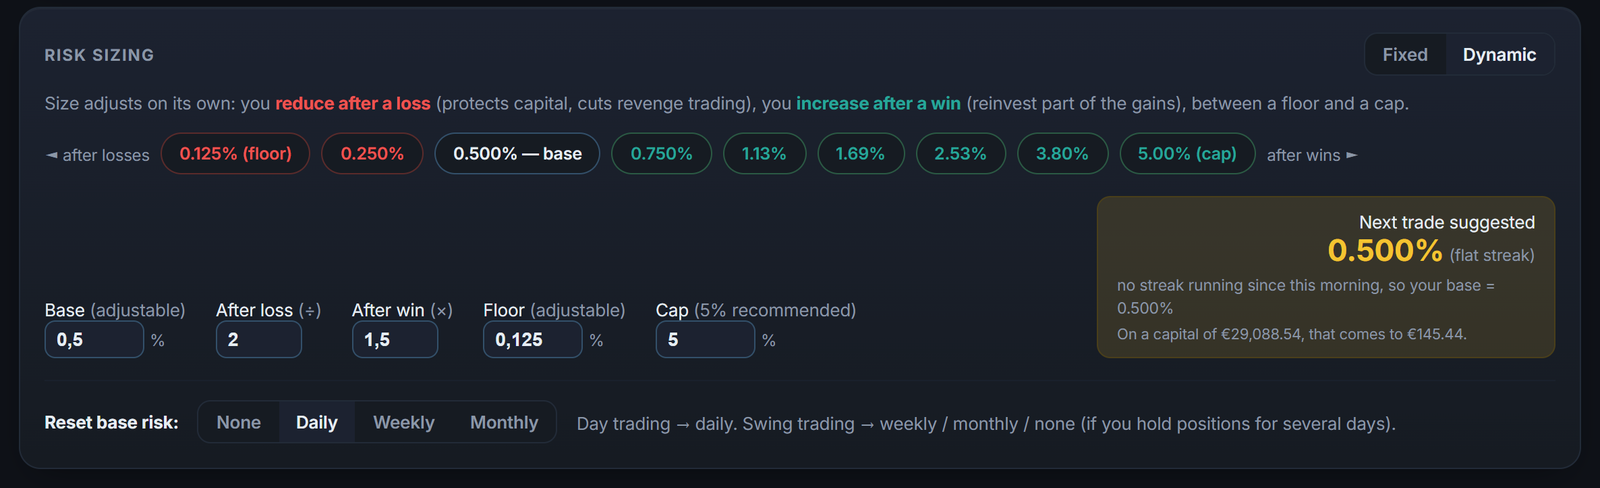
Tradoshi turns risk management from an intention into data. It reads your stops, computes your real risk on each trade that carries one, tracks your maximum drawdown and scores how well you contain it, so your management becomes measurable instead of staying a good resolution.
- Real risk per trade: the percentage of capital engaged is computed from your stop, no entry.
- Management consistency: your average risk shows whether you hold your rule or drift from it.
- Drawdown tracking: your maximum drawdown, the first number to watch.
- Oshi Score: your drawdown control scored as a full axis.
- Built-in calculator: the amount to risk computed before the trade from your capital, plus an estimated lot size to check against your broker's pip value.
Frequently asked questions
What is money management in trading?
It's the set of rules deciding how much you risk on each trade and how you protect your capital: position size, risk percentage, stop loss, daily loss limit. It doesn't create an edge, but it decides what yours becomes: with oversized positions, even a winning system ends up emptying the account.
Fixed or dynamic risk, which is better?
Until your track record is long and profitable, fixed percentage risk is the prudent choice: simple, robust, hard to sabotage. 0.5 to 1% is a starting convention, not a proven figure. Dynamic risk is a refinement to decide cold and in writing, and its defensive version (reducing while the account is dropping) is the one to start with.
How much should I risk per trade?
No percentage is proven right for everyone: the right fraction depends on your edge, which you only know approximately. 0.5 to 1% of current capital is a starting convention. What you can compute is the cost of a streak: ten losses in a row cost 9.6% of the account at 1%, 18.3% at 2% and 40.1% at 5%, and you then need to gain back 10.6%, 22.4% or 67% to return to where you started.
Why is money management more important than strategy?
It doesn't replace it: finding an edge remains the first problem, deciding how much to commit comes next. But for a given strategy, it is what makes the result. In the example worked out by Edward Thorp, a game won 53 times out of 100 pays the most when betting 6% of capital each time, and leads to ruin above about 12%.
What is healthy dynamic risk?
Healthy dynamic risk is decided cold, by objective criteria: reducing your size in drawdown to protect yourself, or adjusting it to market volatility. Dangerous dynamic risk is decided under emotion: loading up because you feel it, increasing to win back. The first strengthens solid management, the second is just over-risk with a nice name.
What's the most serious management mistake?
Varying your risk under the sting of emotion: increasing after a loss to win back, loading up after a gain out of overconfidence, doubling in drawdown to catch up. Doubling after each loss from 1% of capital, six losses in a row cost 63% of the account. The protection is a written rule, and measurement: tracking your real risk makes drift visible before it becomes a habit.
How do I know if fixed risk is actually protecting me, not just in theory?
By tracking your real risk per trade against your intended percentage, not just trusting your plan. Small habits like rounding lot size upward or recomputing risk on stale capital quietly drift your real risk above your rule. A tool that reads your stop and computes real risk after the fact is a reliable way to catch that drift before it becomes a pattern.
Should I ever lower my risk percentage temporarily?
Yes, and it's one of the healthiest forms of dynamic risk. After a meaningful drawdown, during unusually volatile conditions, or while testing an unproven strategy, cutting your risk percentage in half protects you while you're most vulnerable. Restore it only once you have evidence, not just confidence, that your execution has stabilized.