 By Benjamin Roure L'Hermitte
Order book scalping is the kind of subject that hypnotizes traders, and it is costly for those who touch it without a method. You stare at numbers flickering, green and red columns pulsing, and you tell yourself the truth of the market is right there, hidden in that flow. It is, partly. But reading a book gets you nowhere if you do not know what to do with the information in the few seconds it is still valid.
- The order book shows supply and demand in real time, not a prediction of what comes next.
- Big visible orders are not always honest: spoofing and layering are real, and banned.
- Execution speed matters as much as reading skill. A well read book badly executed is worthless.
- Without a journal or discipline, order book scalping quickly turns into a capital vacuum.
What order book scalping actually is
The order book, or the book, is the real time list of the pending orders displayed on an instrument: buyers waiting to get in at a given price, sellers waiting to get out at another. On one side the bid, on the other the ask. Between the two, a spread that breathes with the liquidity of the moment. A trader working the order book does not just look at where price sits, he looks at where price wants to go by watching who is pushing and who is holding the line.
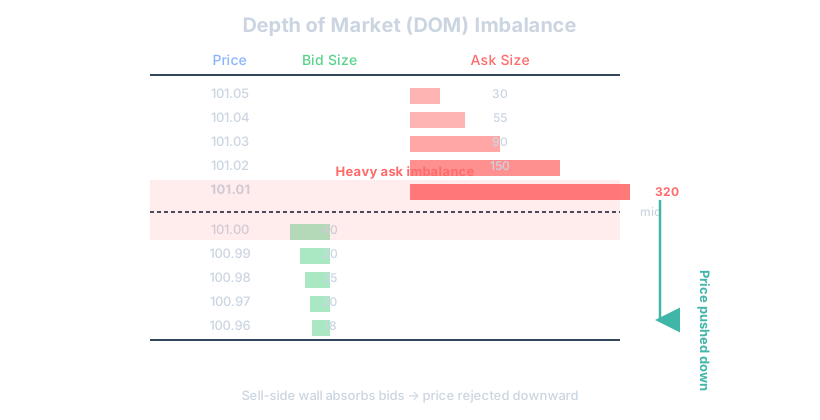
In practice, you open a depth of market window, the famous DOM, and you watch quantities stack up at every price level, for the prices nearest the market (Sierra Chart documentation on the Chart DOM). Trading index futures, for example, you might see 400 contracts stacked on the bid and only 50 on the ask just above. That raw visual imbalance is the scalper's raw material. Research gives it some grounding, and a limit: across 10 liquid Nasdaq stocks in 2014, Gould and Bonart find that the imbalance between the sizes displayed at the best bid and the best ask helps predict the direction of the next mid-price move, and their measurement stops at that next move. There is little to no classic technical analysis here. The trader is reading the mechanics of supply and demand at this exact instant.
This differs from order flow in the broader sense, which also includes time and sales, volume imprints, and delta. The order book is one brick of order flow, the one that shows displayed intentions (resting limit orders), while time and sales lists every executed trade, with its time, direction, price and volume (MetaTrader 5 help on the Depth of Market). A good scalper cross references both constantly, because the book alone can lie to you: in US stocks, the SEC's analysis of the speed of the equity markets found that at most a few percent of posted orders and quotes result in a trade.
The book is only one of four order flow tools. The footprint chart, the heatmap and the volume profile each show something else, and we compare them in footprint charts, DOM and volume profile: the order flow tools.
Why this style attracts so many traders (and disappoints just as many)
There is something mesmerizing about watching a book move. You feel like you are seeing the market's naked truth, without the lag of indicators. No moving average dragging behind, no RSI confirming three candles too late. Just supply and demand, live. For a trader who loves action and hates waiting, that is a soft drug.
The problem is that this apparent truth is also the easiest thing to over interpret. A wall of 500 lots on the bid can vanish in one second, and not necessarily as a trick: the same SEC analysis found that the majority of displayed quotes are cancelled, and that 38.7% of the orders cancelled in the second quarter of 2013 had been in force for half a second or less. You think you are reading real demand. You may be reading an order that will never be filled. And since scalping plays out on tiny moves, a bad read costs you immediately, with none of the recovery time you would get on a swing trade that leaves you hours to adjust.
This style also demands total mental commitment during the session. No multitasking, no scrolling between trades. You are glued to the screen, tense, for whole blocks of time, and that cognitive cost is easy to underestimate.
The elements you need to learn to read in the book
The order book is not just a column of numbers. There are several distinct signals in there, and confusing them distorts the whole read.
- The bid/ask spread: when it suddenly widens, liquidity is pulling out. In US Treasuries, Fleming and Remolona measured that it widens dramatically when a major announcement arrives, when prices are most volatile.
- The depth at each level: a large size that holds its position for several seconds carries more weight than size that flickers in and out.
- Absorption: when a large resting order absorbs aggressive selling without price moving, traders read it as someone defending a level. That is an interpretation, not a certainty.
- Time and sales: the speed and size of executed trades, always to be checked against what the book is showing.
- Iceberg orders: orders that display only a fraction of their size. On CME Globex, the displayed quantity is replenished each time it is filled, until the whole order is depleted (CME Group's page on order qualifiers): only repeated fills at the same price reveal them.
An illustrative example to make this concrete: imagine you are watching a book on a futures contract and you see 300 contracts on the best bid. Price hits that level three times in a row, and each time the size refills almost instantly. That is how an iceberg behaves, though it is not proof of one: other buyers can also reload the level. An experienced scalper reads that as a defended zone and looks for a bounce, rather than blindly shorting just because price tested the level three times.
The trap of spoofing and fake walls
Let's be blunt about this. Spoofing means posting a large order in the book with no intention of executing it, purely to influence how other traders perceive the market and push them to act a certain way. US futures law defines it as bidding or offering with the intent to cancel the bid or offer before execution, and prohibits it.
Layering works on a similar logic: stacking several orders at different price levels to create the illusion of a solid wall, when the whole structure can be pulled in a cascade. EU law describes the two practices together among its indicators of manipulative behaviour: multiple or large orders submitted on one side of the book with no intention of being executed, then removed once a trade has taken place on the other side (Commission Delegated Regulation (EU) 2016/522). And the EU market abuse regulation prohibits market manipulation. The ban has not made them disappear, including on regulated exchanges: in 2020, the CFTC, the US futures regulator, ordered JPMorgan to pay $920 million over hundreds of thousands of spoof orders placed from 2008 to 2016 in precious metals and Treasury futures.
How do you protect yourself without playing financial detective? By watching for persistence. A wall that stays stable for several seconds, that genuinely absorbs fills, carries far more credibility than a wall that appears right before price approaches and disappears at the last moment. This is a skill built through repeated observation, not a weekend of YouTube tutorials. And honestly, if you are just starting out, it makes more sense to first understand scalping in its broad strokes before diving into fine grained book reading.
Execution: the part everyone underestimates
Reading the book is one thing. Pressing the button at the right moment, with the right size, with zero lag, is another. In order book scalping you are playing on moves of a few ticks. A latency spike, a sluggish platform, a misplaced click, and your theoretical edge evaporates before it ever existed. Order flow platforms come with hardware requirements of their own: our guide to the trading computer goes through the figures their vendors publish, part by part. And the book itself reads best on a screen of its own, turned to portrait: one of the cases covered in our guide to the best monitor for trading.
This is why this style depends on the market and the account as much as on the read. On a futures contract, orders meet in the exchange's book. In retail forex there is no central marketplace where buyers and sellers meet, and the dealer sets the execution price (the National Futures Association's guide to retail forex); in MetaTrader 5, according to its help, the book you see can then be built from the broker's quotes alone. That is not a minor technical detail, it is a component of the edge itself. Speed matters just as much: according to the same SEC analysis, about a quarter of order cancellations in US stocks happen within 50 milliseconds of the order being posted. You can have the best read in the world, but slow execution leaves you facing a price that is no longer there.
The same logic applies to position risk management. Mental stops do not exist in order book scalping, there is no time to think. You need an automatic stop, often very tight, defined before you even enter. This is where calculating your position size correctly becomes vital: on a scalp with almost no margin for error, an oversized position turns a small execution slip into serious account damage.
The specific psychological cost of this style
Trading psychology gets discussed in general terms all the time, but order book scalping has its own sharper mental traps, more acute than on longer timeframes. The frequency of decisions is enormous. You might take fifteen, twenty, sometimes thirty trades in one session. Each small loss, on its own, means nothing. But the accumulation over a rough morning can push you toward tilt without you even noticing it happening.
This is the perfect playground for revenge trading, because the speed of the loss-then-retry cycle leaves you no room to step back. On a swing trade, you lose, you close the screen, you come back tomorrow with a clear head. On a scalp, you lose, and five seconds later the book is already flashing a new opportunity screaming 'get in now'. That compression of time between failure and the temptation to jump back in is what makes this style so psychologically dangerous.
FOMO also takes a particular shape here: watching a move unfold while you hesitate a split second too long, then wanting to 'make up for it' on the next trade with a bigger size. That is exactly the mechanism described in the piece on FOMO in trading, except here everything happens at a speed that gives you almost no chance to catch yourself before your finger hits the button.
Building a realistic routine for this trading style
Order book scalping is not compatible with improvisation. It needs a structured session, rules written down in advance, and the ability to stop cold the moment something feels off. Here are five rules to frame a session.
- Decide in advance which instruments you follow (one or two, never more) and know their liquidity behavior at different hours of the day.
- Set a fixed position size for the whole session, not one that grows after every win.
- Set a hard limit on consecutive losses before you stop, because the fast pace hides the decline in your mental state.
- Log each trade right after taking it, even one line, so you don't lose track of what worked and what failed.
- Build in mandatory breaks every 20 to 30 minutes. Focus on a DOM degrades fast with fatigue.
On that last point, it is tempting to believe you can stay sharp for two straight hours on a DOM. We have no measurement to cite for an order book, but vigilance research argues for caution: in an experiment by Claypoole, Dever, Denues and Szalma on 84 participants, the ability to detect signals declined from one period to the next over a 24-minute watch. Short breaks are a reasonable precaution, not a guarantee.
Why this style is hard to make work
Here's an uncomfortable truth: order book scalping punishes a trader who is undercapitalized, under equipped on execution, or mentally unprepared for the pace. It is easy to watch a few videos of an experienced trader calling moves with apparent ease and assume the skill transfers instantly. It doesn't. What you're watching is long practice compressed into a five minute clip.
There is also a structural mismatch between order book scalping and the retail trading psychology most people bring to the market. This style rewards patience within speed, a strange combination: you need to wait for the right imbalance, but once it appears you have almost no time to act. The two ways to get it wrong are to force trades out of boredom, which is a textbook case of overtrading, or to freeze at the critical moment and miss the window entirely.
Add to that the fee structure. Scalping generates a high volume of trades, and each one carries a cost, whether it's commission, spread, or slippage. With a target of only a few ticks, that cost has to be earned back before the trade reaches break even. A strategy that looks profitable on paper can bleed out once real transaction costs get factored in. We have no measurement to cite for order book scalpers; the closest covers day traders on the Taiwan Stock Exchange from 1995 to 1999, where Barber, Lee, Liu and Odean found that heavy day traders earned gross profits that did not cover their transaction costs, and that more than eight out of ten day traders lost money in a typical six-month period. This is precisely why tracking your profit factor matters more here than almost anywhere else: a high win rate built on tiny wins can still be a net loser once costs eat the margin.
Risk rules that actually fit this pace
Generic risk management advice does not always translate cleanly to order book scalping, because the time horizon is so compressed. Still, the core principle holds: you should know, before you click, exactly how much you stand to lose if the read is wrong. Risking a small, fixed percentage of capital per trade, the logic explained in why risking 1 percent changes everything, applies just as much here, maybe more, because the sheer number of trades multiplies any sizing mistake many times over in a single session.
A daily loss limit is not optional in this style, it is survival gear. Given the frequency of trades, a bad morning can spiral into a catastrophic day within minutes if there is no hard stop. Traders on funded accounts meet the rule in writing: at FTMO, for example, the Maximum Daily Loss is a limit that account equity cannot drop below, and falling under it counts as a rule violation (FTMO's trading objectives). Retail traders have no such external daily loss limit and have to set their own.
There is also the question of correlated exposure. If you scalp two instruments that tend to move together, say two index futures, a bad read on one often means a bad read on both at the same time. That hidden overlap is worth understanding through the lens of position correlation, because what looks like diversification across two charts can actually be one single, doubled bet.
How Tradoshi helps you
Order book scalping produces a lot of trades, fast, and that volume is exactly what makes honest self assessment hard without a proper record. Tradoshi's trading journal lets you import trades automatically from MT5, MT4, cTrader or crypto exchanges, or log them manually, so a 30 trade session does not vanish into a blur of half remembered clicks and gut feelings by the end of the day.
The statistics module gives you your win rate, profit factor, expectancy, average win/loss ratio and R-multiple, all useful to check whether your book reading edge is real or just noise dressed up as skill over a small sample. The position size calculator and customizable risk rules help you keep sizing consistent trade after trade, which matters enormously in a style where one oversized click can undo a week of small, disciplined gains.
Because this style is mentally taxing, the emotional check-in before a session and the emotion and performance link analysis can help you notice, over time, whether your worst trades cluster around fatigue, frustration after a loss, or a specific hour of the day. Trade Review lets you replay a trade, tag trades with labels you choose yourself, and check plan adherence, so you can see clearly whether a losing streak came from bad reads or from abandoning your own rules under pressure. None of this replaces screen time on the book itself, but it gives you the record to learn from that screen time honestly.
A realistic path if you want to try this style
Nobody should start live trading real capital on the order book on day one. The realistic path looks more like this: spend weeks just watching the DOM without trading, narrating out loud what you expect price to do next, and checking yourself against what actually happens. It feels slow. It is slow. It is also how a read gets built, one boring, uneventful session at a time.
Once you start trading small size, keep the size genuinely small, small enough that a string of losses does not touch your confidence or your account meaningfully. Scale up only when your statistics, not your gut feeling, tell you the edge holds across dozens of sessions and different market conditions. Fast markets forgive almost nothing. Slow, deliberate progress is the only sane way in.
Frequently asked questions
Is order book scalping suitable for beginners?
Generally no. It demands fast pattern recognition, low latency execution and strong emotional control under pressure, all things that take time to build. Beginners are usually better served starting with slower, more forgiving styles before attempting this one.
What is the order book in trading?
The order book is the real time list of the pending orders displayed on an instrument: buyers waiting on the bid, sellers waiting on the ask, and a spread between the two. A depth of market window, the DOM, shows the quantities stacked at each price level nearest the market. It shows displayed intentions, not executed trades.
What is spoofing in trading?
Spoofing is posting a large order with no intention of executing it, purely to influence other traders' perception of supply or demand. The order is pulled before it would be filled. US futures law prohibits it and EU law lists it among its indicators of market manipulation, which has not made it disappear.
How is order book scalping different from order flow trading?
The order book shows resting, displayed orders (intentions), while broader order flow analysis also includes time and sales, executed volume and delta, meaning what actually traded. Order book reading is one component of the wider order flow approach.
Do I need a special broker for this style?
First you need a market whose book is an exchange's book, such as futures: in retail forex, the book you see can be built from the broker's quotes alone. Then execution speed matters, since a slow order routing path can erase a theoretical edge entirely.
How many instruments should I follow at once?
One or two that you know intimately, including how their liquidity behaves at different times of day. Watching too many books at once splits attention and degrades reading quality.
What is an iceberg order?
It is a large order that only displays a small portion of its true size in the book. It reveals itself through repeated fills at the same price level without the visible size ever seeming to shrink.
How long can I realistically stay focused on a DOM?
We have no measurement to cite for a DOM. In laboratory vigilance tasks, detection declines with time on watch, including within a 24-minute watch in an experiment published in Human Factors in 2019. Building short breaks into the session is a reasonable precaution.
Is order book scalping profitable long term?
It can be for traders with the right infrastructure, discipline and enough screen time to build a genuine read, and nothing guarantees it. Transaction costs and execution lag make it a much harder edge to sustain than it looks from the outside.
How do transaction costs affect this style?
Because scalping generates a high number of trades, commissions, spread and slippage accumulate fast. A strategy that appears profitable in theory can turn into a net loser once real costs are factored in.
Should I track every single scalp trade in a journal?
Yes, even briefly. With the trade frequency involved, memory alone cannot tell you honestly whether your edge is real. A logged record, even one line per trade, is the only reliable way to review performance later.